The Long and Short
An active week for hybrid issuance
This material is a Marketing Communication and does not constitute Independent Investment Research.
Corporate borrowers have rushed back to the investment grade market as usual after Labor Day with non-bank hybrids among the most active sectors. With several new deals pricing, a fresh look at pricing models can show where those bonds fit and help investors compare value across the segment’s cohorts. Overall, the non-bank hybrid sector continues to offer attractive valuation with opportunities to move down in structure to add yield.
In $73.2 billion of issuance after Labor Day, five non-bank hybrid issuers priced $5.9 billion across nine tranches, with two additional financial hybrids also coming to market. Ameren (AEE: Baa2/BBB- hybrid rating) opened the week Tuesday with a 30NC5 at 6.45%. On Wednesday, Fortis (FTSCN: BBB/BBB-) priced a 30NC5 and 30NC10 at 6.625% and 6.875%. Plains All American (PAA: Baa3/BB+) brought a 30NC5 at 6.75% and a 30NC10 at 7.00%, while Rogers Communications (RCICN: Ba2/BB) priced comparable structures at 7.15% and 7.40%. Vistra (VST: Ba2/BB/BB) was the last issuer to enter the market, making its first hybrid deal with tranches at 7.00% and 7.25%. VST’s new issues do not show up in the exhibits here because they priced late.
All the new issues include coupon floors, which continue to draw investors concerned about extension risk amid global rate uncertainty. Verizon Communications, which returned to the hybrid sector several weeks ago, remains the only issuer to go further by adding coupon step features. As these protections have become standard over the past year, relative value opportunities remain in some recent and older vintages. In those bonds, moderate call protection comes with some of the most attractive spread and yield compensation compared with similar senior unsecured bullets.
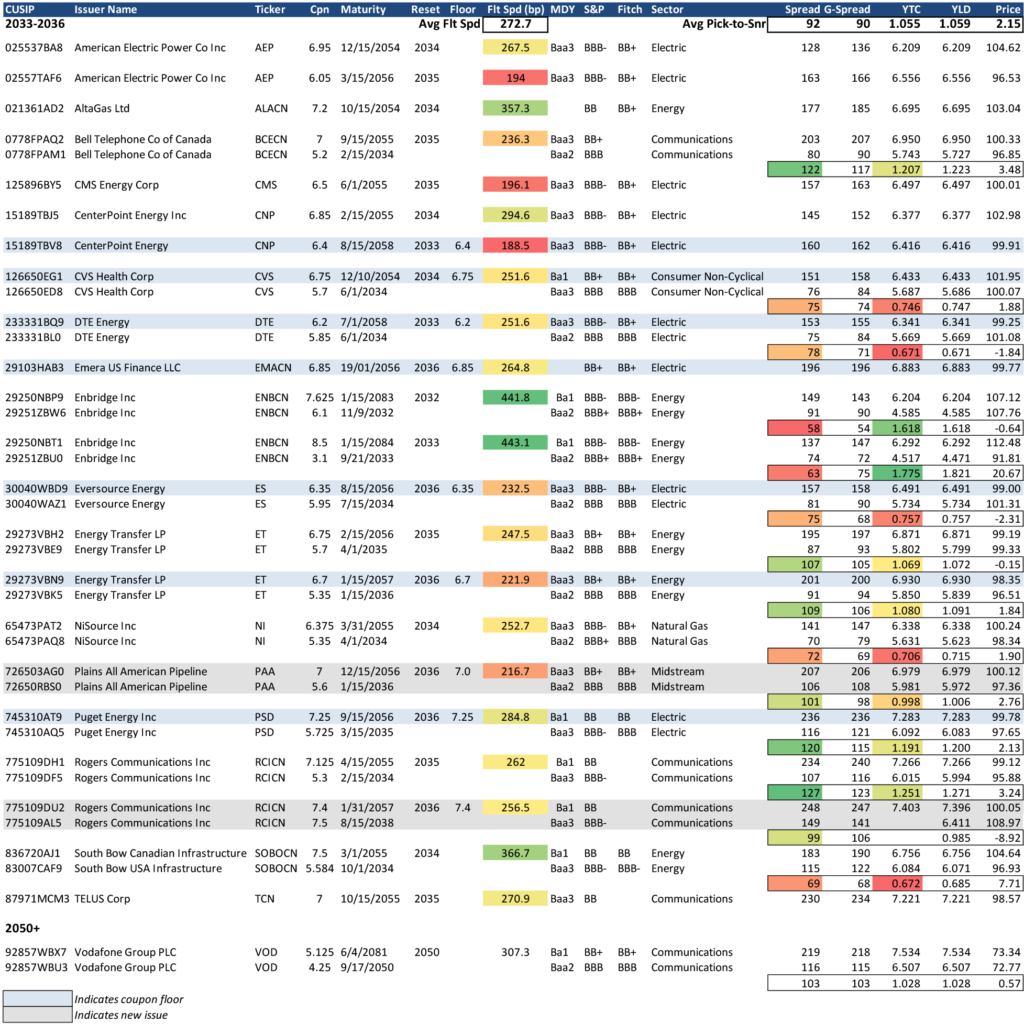
In the four exhibits below, the middle color scale shows how each bond’s back-end floating rate compares with others in the group. The highest spread, which provides the most call protection, is shown in green; the lowest is shown in red. The two color scales on the right show spread and yield-to-call pickup versus senior bullet securities. Higher pickups are shown in green and lower pickups in red. In general, stronger call protection means lower spread and yield pickup versus bullets. Some hybrid bonds in the study do not have comparable senior securities.
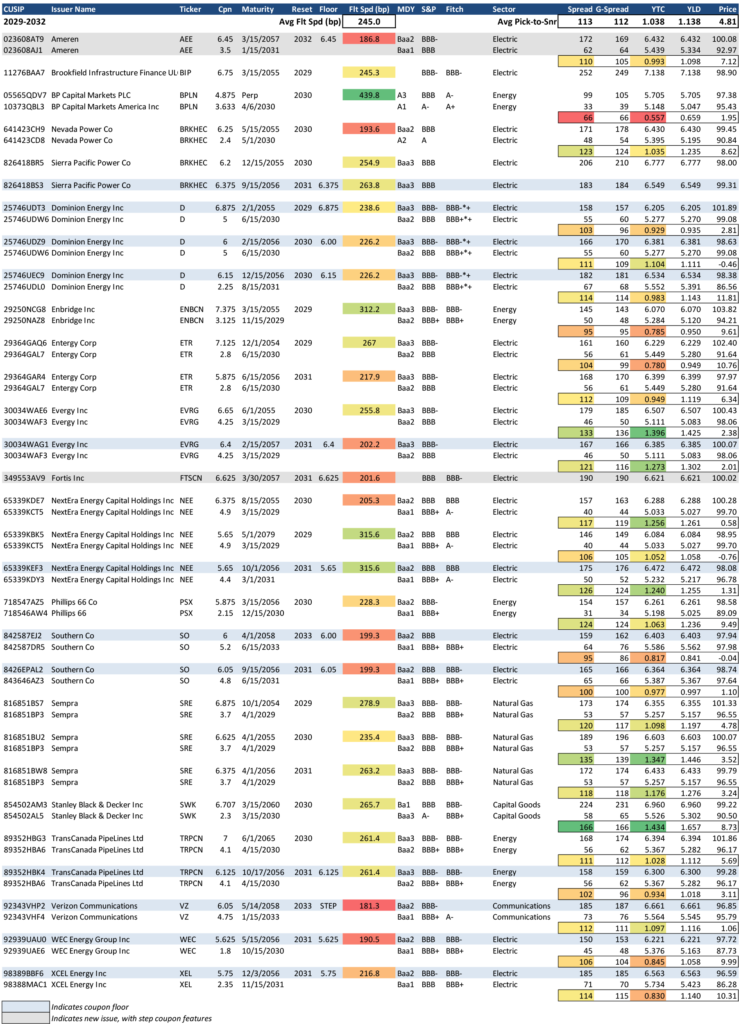
Exhibit 1 lists investment-grade non-bank hybrids with roughly five-year calls (2029-2032) compared with similar five-year senior bullet securities. This is the largest cohort in the investment-grade hybrid universe. Bonds with coupon floors are highlighted in blue, and new issues are shown in gray. The average spread pickup for hybrids versus seniors has tightened modestly since May and now stands around +110 bp to +115 bp. Aged vintage bonds that appear attractive versus newer structures include:
- EVRG 6.65% ’55 (+255.8 bp back-end)
- SRE 6.875% ‘54 (+278.9 bp back-end)
- SRE 6.625% ‘55 (+235.4 bp back-end)
- SRE 6.375% ‘56 (+263.2 bp back-end)
- SWK 6.707% ‘60 (+265.7 bp back-end)
Exhibit 1. 5-year Call IG-Rated Non-Bank Hybrids vs Senior Bullets
Source: Santander US Capital Markets LLC, Bloomberg/TRACE YAS price indications only
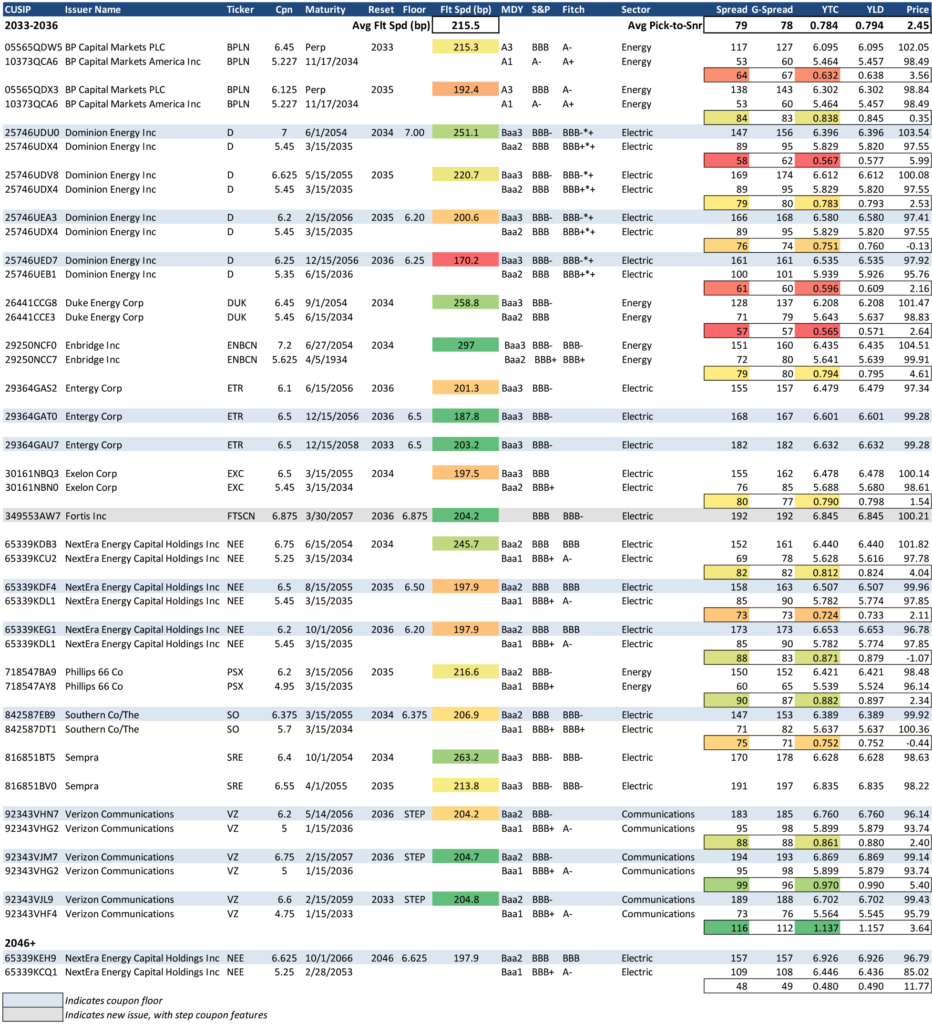
Exhibit 2 lists investment-grade securities with roughly 10-year calls (2034-2036) compared with similar 10-year senior bullets. Recent issues with coupon floors on the back end are highlighted in blue, and new issues are shown in gray. The average hybrid spread pickup versus seniors is about +75 bp to +80 bp. Some older and recent bonds that appear attractive include:
- D 6.625% ‘55 (+220.7 bp back-end)
- VZ 6.75% ‘57 (+204.7 bp back-end, step feature)
- VZ 6.6% ‘59 (+204.8 bp back-end, step feature)
Exhibit 2. 10-year Call IG-Rated Non-Bank Hybrids vs Senior Bullets
Source: Santander US Capital Markets LLC, Bloomberg/TRACE YAS price indications only
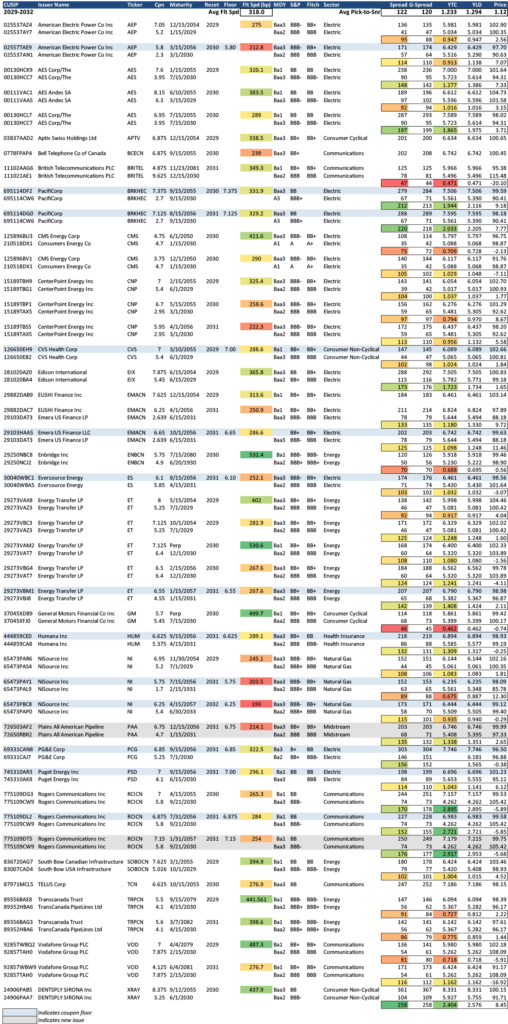
Exhibit 3 lists high-yield non-bank hybrids with roughly five-year calls (2029-2032) compared with similar five-year senior bullets. This is the largest cohort in the full hybrid universe. Bonds with coupon floors are highlighted in blue, and new issues are shown in gray. The average hybrid spread pickup versus seniors is about +120 bp to +125 bp. Some of the bonds that appear attractive include:
- BRKHEC 7.375% ‘55 (+331.9 bp back-end, floored)
- BRKHEC 7.125% ‘56 (+329.2 bp back-end, floored)
- EIX 7.875% ‘54 (+365.8 bp back-end)
- ET 6.55% ‘56 (+267.6 bp back-end, floored)
Exhibit 3. 5-year Call HY-Rated Non-Bank Hybrids vs Senior Bullets
Source: Santander US Capital Markets LLC, Bloomberg/TRACE YAS price indications only
Exhibit 4 lists high-yield securities with roughly 10-year calls (2034-2036) compared with similar 10-year senior bullets. Recent issues with coupon floors on the back end are highlighted in blue. The average hybrid spread pickup versus seniors is about +90 bp to +95 bp. Some bonds that appear attractive include:
- ET 6.75% ‘56 (+247.5 bp back-end)
- ET 6.7% ‘57 (+247.5 bp back-end, floored)
- PSD 7.25% ‘56 (+284.8 bp back-end, floored)
- RCICN 7.125% ’55 (+262 bp back-end)
Exhibit 4. 10-year Call HY-Rated Non-Bank Hybrids vs Senior Bullets
Source: Santander US Capital Markets LLC, Bloomberg/TRACE YAS price indications only
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.