The Long and Short
Revisiting Ally Financial as a value among bank credits
This material is a Marketing Communication and does not constitute Independent Investment Research.
Private credit fears continue to leave their mark on parts of the investment grade market. Consumer finance companies and banks with any private credit exposure, such as Ally Financial (ALLY: Baa3/BBB-/BBB-), are among those that still reflect these concerns. There’s reason to believe that ALLY corporate bonds are still being undervalued on the heels of very strong second quarter results.
One clear bone of contention in the market last year was the aggressive growth in private credit, which weighed heavily on issuers like ALLY and similarly positioned peers. Many of those concerns have dissipated in recent months, as the market has seen a stark recovery in private credit-exposed lenders, most notably in BDCs. Still, similar to the threat that AI poses to traditional software and technology operators, there remains an undercurrent of risk that could easily resurface with similar idiosyncratic headlines that moved the market in late 2025.
ALLY’s inclusion among this private credit cohort has seemed highly overblown. Direct exposure to middle market lending and private credit appears limited to its roughly $13.7 billion portfolio of non-auto corporate finance loans amidst total loans of about $140 billion. And credit performance in this small portion of ALLY’s lending has remained remarkably consistent. The last delinquency/non-accrual in their non-auto corporate finance portfolio was reported roughly eight years ago. Furthermore, overall lending at Ally Bank to non-bank financial institutions (NBFI) represents just 2.95% of total assets compared to an average level of about 7% across most US banks. Growth in that segment for ALLY has ramped up a bit to 34% year-over-year as of the most recent quarter but is relatively neutral to the rest of the industry, while the 5-year growth rate of just 214% is running significantly below peers.
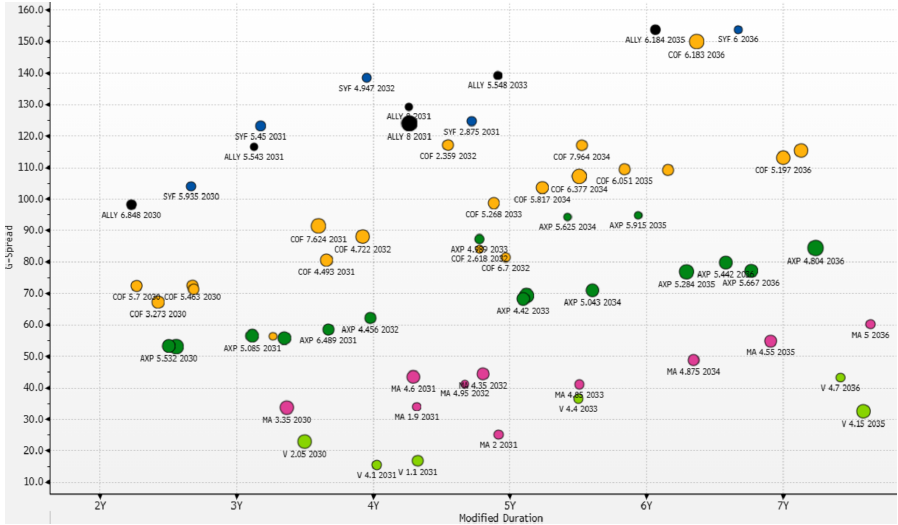
While ALLY credit instruments rightfully trade in a tighter range than the most conservative cohort of low-‘BBB’ middle-market lenders, such as BDCs, they still reflect a substantial discount to most similarly-positioned consumer finance operators (Exhibit 1). This presents an opportunity to increase exposure and consider alternatives to move down in structure to ALLY’s subordinated and hybrid instruments for incremental spread and yield. In May of this year, ALLY issued a PerpNC5 hybrid structure (rated Ba2/BB-/B+), which remains priced near its launch level of approximately 7.1%. This represents a premium of over 140 bp to commensurate ALLY 5-year senior bullets. The average pick for similar ‘BB’-rated hybrid structures with roughly 5-year calls more typically falls below 130 bp.
Exhibit 1: ALLY still trades wide to investment-grade consumer finance peers
Source: Santander US Capital Markets LLC, Bloomberg/TRACE spread/price indications only
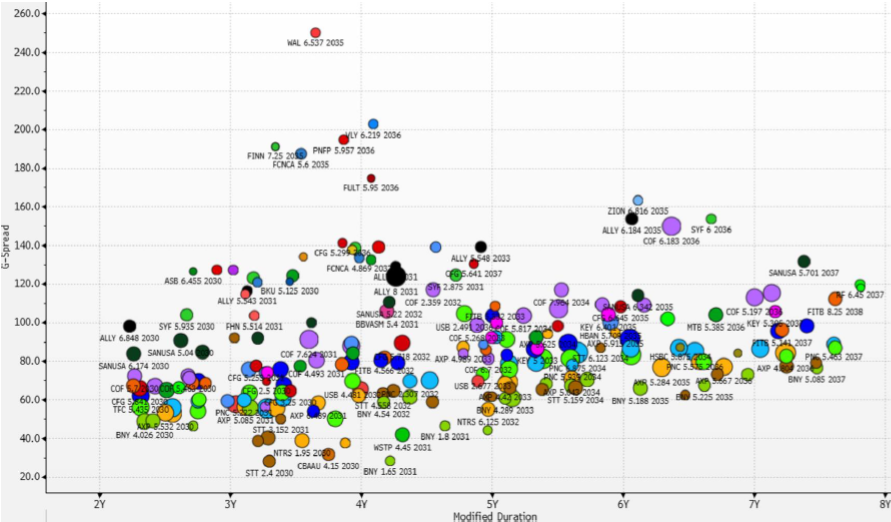
ALLY’s attractiveness to the broader regional banking sector is also apparent with mostly only outliers and the few lower-BBB regional banks trading wide of the ALLY curve (Exhibit 2).
Exhibit 2: ALLY also trades wide to broader regional bank peers
Source: Santander US Capital Markets LLC, Bloomberg/TRACE spread/price indications only
ALLY reported strong second-quarter operating results this week, which continued to alleviate concerns about credit deterioration in auto lending. In the second quarter, the net charge-off rate declined 18 bp to 1.57%, which was the sixth consecutive quarter of year-over-year improvement, while delinquencies declined 8 bp year-over-year to 4.80%. These levels remain somewhat elevated to pre-pandemic levels, but the lack of acceleration continues to demonstrate ALLY’s conservative lending standards across its franchises. The provision for credit costs did increase a modest amount ($46 million) year-over-year to $384 million as reserves increased $36 million year-over-year to $3.58 billion. This all appears commensurate with the gradual seasoning of the auto portfolio, versus an indication of active credit deterioration.
ALLY increased its concentration in auto lending last year through the sale of its credit card and mortgage businesses. The loss of those businesses could also make the lender slightly more susceptible to deposit migration for its all-online deposit base. However, in doing so the company significantly enhanced net interest margins going forward (approximately 40 bp at the time), reduced expected credit losses, and can focus more on its core competencies. The digital deposit base results in higher deposit betas relative to typical lenders but greatly reduces costs associated with brick-and-mortar branch banking. ALLY reported 18 bp in year-over-year net interest margin (NIM) growth to in the second quarter to 3.63%.
ALLY’s digital deposit platform remains relatively liability sensitive and subject to competitive rates for depositors. Rising interest rate trends on recent geopolitical events put pressure on profit margins. Nevertheless, deposits represent approximately 87% of funding, which is up from 66% just seven years ago. Meanwhile, ALLY’s reliance on brokered deposits, which are considerably less sticky and potentially more costly, are less than 4% off a recent peak of over 8% in 2022 and as high as 14% back in 2018. ALLY also benefits from an extremely low level of uninsured deposits (just roughly 8%) relative to typical bank lenders (anywhere from 20 to 50%, COF is 15%) given its unique auto-focused loan mix.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.