The Big Idea
The rising dispersion of credit spreads
This material is a Marketing Communication and does not constitute Independent Investment Research.
Debt markets rarely have drawn such sharp lines between credits as they do now. Spreads in technology and communications have jumped to some of their widest levels in five years, while spreads in energy, utilities, health care, industrials, materials and consumer staples have moved almost as sharply the other way. As a result, the gap in spreads across sectors is the widest in five years. It will likely grow until Fed policy, corporate results or both rein it in.
Credit spreads take very different paths
Spreads across credit sectors have taken sharply different paths in the past year (Exhibit 1A). Each sector tends to trade at a typical spread to the overall investment grade index. Bank and insurer debt, for instance, usually trades wide. So it helps to convert each sector’s spread into a standardized score, or z-score, relative to the index. Those scores show dispersion rising steadily. A year ago, every investment grade sector traded within one standard deviation of its average spread to the index. Today, some sectors trade about three standard deviations wide and others three standard deviations tight. Dispersion has gone from one of its lowest levels in five years to its highest (Exhibit 1B).
Exhibit 1A: Sector spreads have taken sharply different paths in the past year
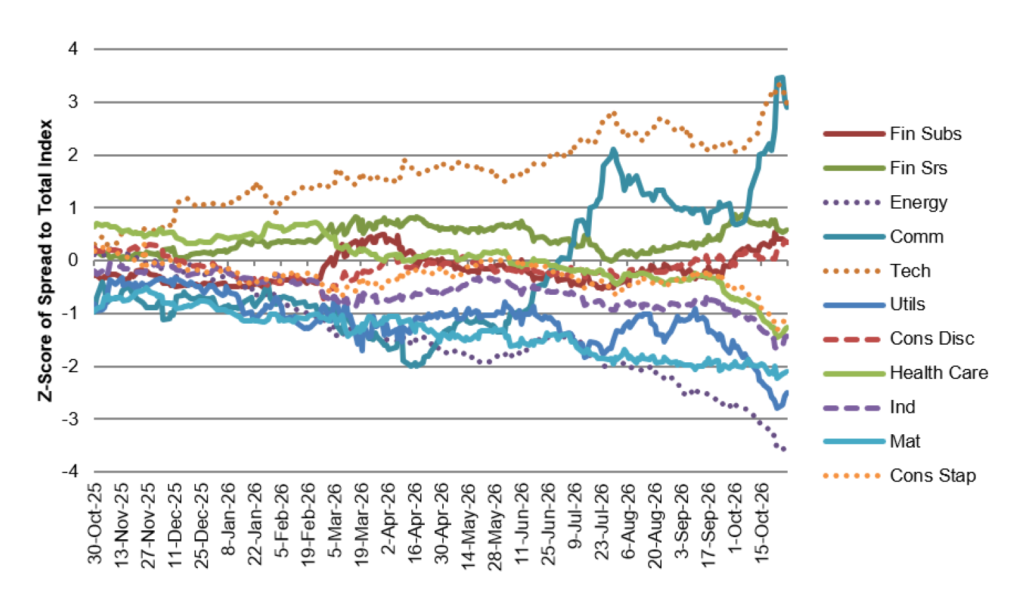
Note: Data shows each sector’s standardized OAS to the Bloomberg investment grade corporate index. Each sector’s spread to the index is converted to the number of standard deviations from its five-year average: (Current sector OAS spread to the index – Average sector OAS spread to the index)/(Standard deviation of OAS spread to the index).
Source: Bloomberg, Santander US Capital Markets.
Exhibit 1B: Spread dispersion hits a five-year high
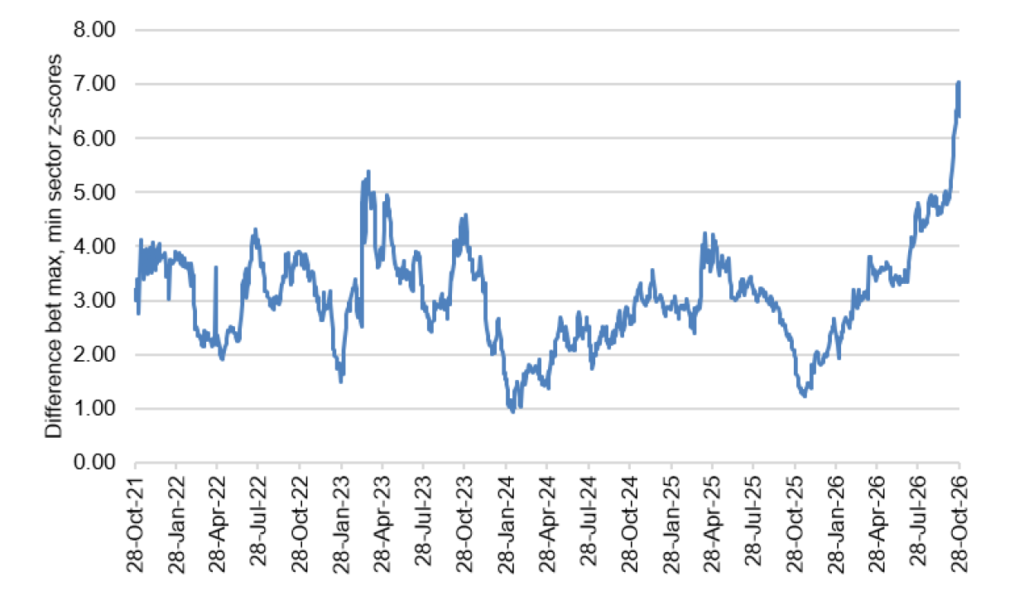
Note: Data shows the difference between the highest and lowest standardized sector spreads to the index OAS.
Source: Bloomberg, Santander US Capital Markets
The dispersion reflects clear differences in risk. A few examples:
- Technology has faced a flood of new debt and worries that heavy capital spending will drain free cash flow and add leverage, pushing spreads to 2.97 standard deviations above average
- Communications spreads have widened on Meta’s heavy capital spending and, more recently, on weaker-than-expected earnings at Charter Communications, reaching90 standard deviations above average
- Energy has moved the other way as the US-Iran war has kept prices near five-year highs, tightening spreads to 3.45 standard deviations below average
- The AI buildout may have hurt technology debt overall, but it has boosted demand for electricity and water, helping tighten utility spreads to 2.50 standard deviations below average
- Materials companies have ridden rising prices to spreads 2.10 standard deviations below average
- And investors diversifying away from technology, along with a generally strong economy, have arguably helped tighten spreads in industrials, health care and consumer staples to 0 to 1.5 standard deviations below average
Dispersion or reversion
As long as heavy tech capital spending continues, spread dispersion across credit will likely hold or widen. Recent earnings calls from the largest tech companies—Alphabet, Amazon, Meta, Microsoft, Oracle and SpaceX—suggest capital spending could climb from $863 billion this year to $1.33 trillion next year. That should push tech debt spreads even wider. The same spending should help tighten spreads in utilities and in sectors investors use to diversify away from tech. A generally strong economy should support spreads in industrials and consumer staples.
On the other hand, Fed efforts to fight inflation could pull spreads back together. Even if higher rates fail to rein in tech spending, they should cool more traditional sectors and slow spread tightening outside of technology. The most rate-sensitive sectors could even widen, narrowing dispersion from the tight end.
Weak tech results could also narrow spread gaps. Lower revenue or falling free cash flow at the big AI builders might raise fundamental risk, but it could also slow capital spending and ease supply pressure on credit markets. Utilities and other sectors lifted by that spending could give back some gains, and dispersion could narrow.
For now, it’s hard to add tech exposure while AI builders keep signaling they’ll need even more funding in 2027 and as the Fed takes a measured approach to bringing down inflation. Dispersion will likely hold or rise. At the very least, it makes sense to wait until the Fed starts tapping the brakes on the economy. That may be the time to position for credit spreads to converge.
* * *
The view in rates
The market is pricing another 18 bp of Fed tightening by December and then 36 bp more—for a total of 54 bp—before the end of 2027.
A break in the AI rally could hit credit and the broader economy and lead recession to drag rates lower, but that possibility looks remote. CoreWeave has shown some vulnerability, so highly leveraged balance sheets should be the place to look for AI weakness. However, the AI build among hyperscalers seems almost immune to higher rates for now.
Apart from the AI rally, the market is clearly concerned about the impact of higher rates on other parts of the economy—housing, automotive, other rate-sensitive sectors. The question is the level of rates where those sectors start to noticeably slow.
Key market levels:
- Three-month term SOFR traded late this week at 406 bp, unchanged in two weeks.
- The 2-year Treasury note traded Friday at 4.59%, down 17 bp in two weeks. The 10-year note traded at 4.93%, down 16 bp in two weeks.
- The Treasury yield flattened sharply in the last two weeks, with 2s10s at 34 bp, steeper by 1 bp. The 5s30s traded late in the week at 59 bp, steeper by 7 bp in the last two weeks.
- The 10-year inflation breakeven traded Friday at 234 bp, up 1 bp in two weeks. The 5-year, 5-year forward breakeven was 221 bp, down 7 bp. The 10-year real rate ended the week at 259 bp, down 18 bp.
The view in spreads
Risk spreads are moving in very different directions with credit broadly wider—with wide dispersion across sectors—and MBS tighter. The Bloomberg US investment-grade corporate bond index option-adjusted spread traded late in the week at 87 bp, wider by 4 bp in the last two weeks. Nominal par 30-year MBS spreads to a blend of 5- and 10-year Treasury yields were 125 bp, wider by 2 bp. Par 30-year MBS Treasury option-adjusted spreads closed at 32 bp, tighter by 3 bp in the last two weeks.
The view in credit
Persistent high rates should put pressure on more leveraged balance sheets. Large companies have healthier balance sheets than smaller ones. Middle- and higher-income consumers also carry relatively little debt and have strong liquidity and wealth.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.