The Big Idea
A story of rising rates, higher volatility and wider spreads
This material is a Marketing Communication and does not constitute Independent Investment Research.
Rising interest rates from June through September and a burst in volatility toward the end left their marks all over the investment performance of US fixed income. Sectors with the longest duration and most exposure to volatility lost the most. The quarter showed once again that making rate calls is a tough business. Positioning in quality credit spreads looks like a better proposition.
Losses in most parts of fixed income
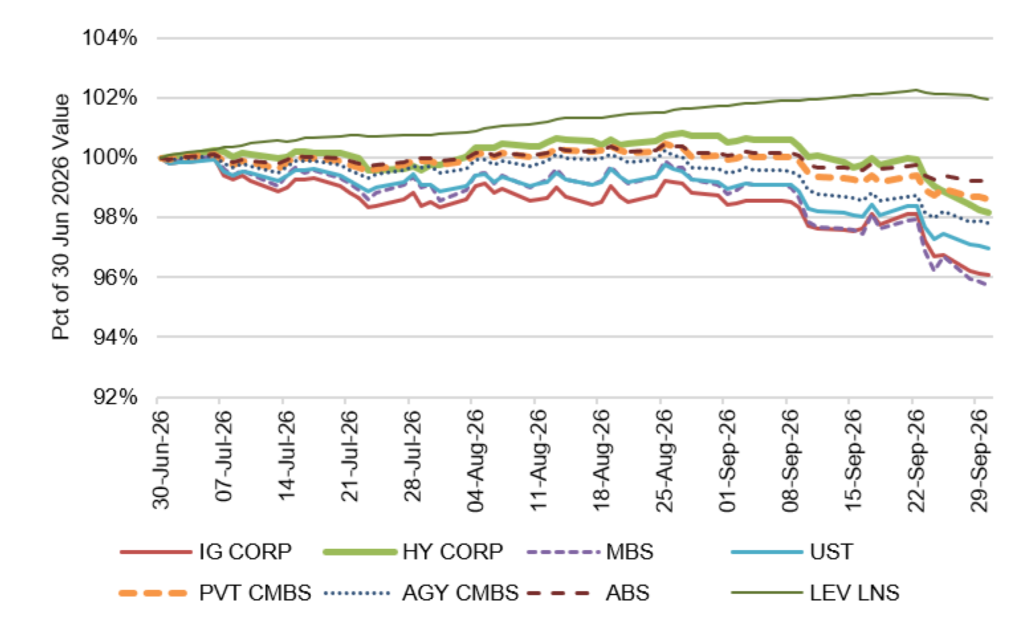
Only leveraged loans among the major sectors of US fixed income managed to post gains from June through September. Loans returned 1.95% with the next closest sector, ABS, posting a 0.79% loss (Exhibit 1). Private CMBS lost 1.37%, high yield corporate debt lost 1.82%, agency CMBS lost 2.20% and Treasury debt lost 3.04%. Investment grade corporate debt lost 3.94% and MBS lost the most at 4.25%.
Exhibit 1: The path of returns across US fixed income shows a rough September
Source: Bloomberg, Santander US Capital Markets
Rising rates across the yield curve took their toll on prices throughout most of the quarter with returns falling roughly in line with the duration of each sector. Then in September, a surge in option-implied rate volatility from 75 on the MOVE index at the start of the month to 110 at the close helped widen spreads and send returns lower in every sector. Sectors particularly sensitive to volatility fell hard, with MBS losing 97 bp of return partly from higher volatility and high yield losing 140 bp.
Risk offered no offsetting return
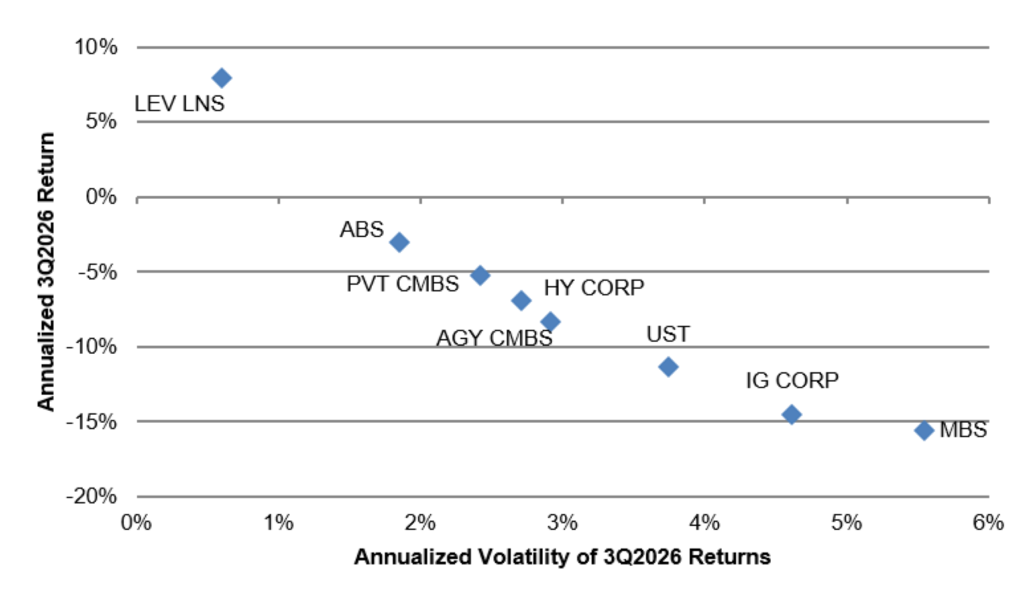
The riskiest assets during the quarter offered no offsetting return. In fact, it was just the opposite. Sectors with the best returns delivered them with the least risk or volatility, and sectors with the worst returns delivered them with the most risk (Exhibit 2). At one extreme, for instance, leveraged loans delivered the highest annualized return of 7.91% from June through September with the lowest annualized standard deviation of only 0.60%. MBS, at the other extreme, delivered a top annualized loss of 15.6% loss with the highest standard deviation of 5.54%.
Exhibit 2: Risk offered no offsetting return from June through September
Source: Bloomberg, Santander US Capital Markets
September hit excess return hard
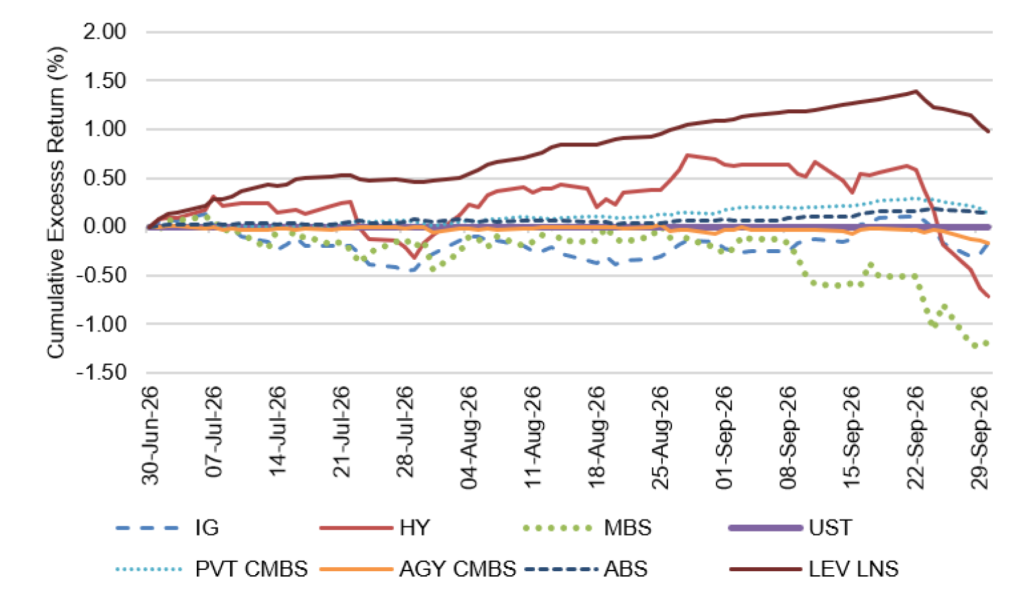
Stripping out the price impact of interest rates and leaving only returns from excess interest income and changing yield spreads significantly reduces the dispersion across sectors and highlights performance in sectors insulated from volatility risk. Leveraged loans posted the most excess return at 98 bp with ABS next at 14 bp. Private CMBS posted 13 bp of gains, wider agency CMBS spreads led to added losses of 17 bp and wider investment grade corporate spreads to added losses of 17 bp. Wider high yield spreads added 71 bp to losses, and wider MBS spreads added 118 bp to losses. Excess return plunged in September as volatility rose.
Exhibit 3: Excess returns plunged in most sectors in September
Source: Bloomberg, Santander US Capital Markets
Rates and volatility did most of the damage
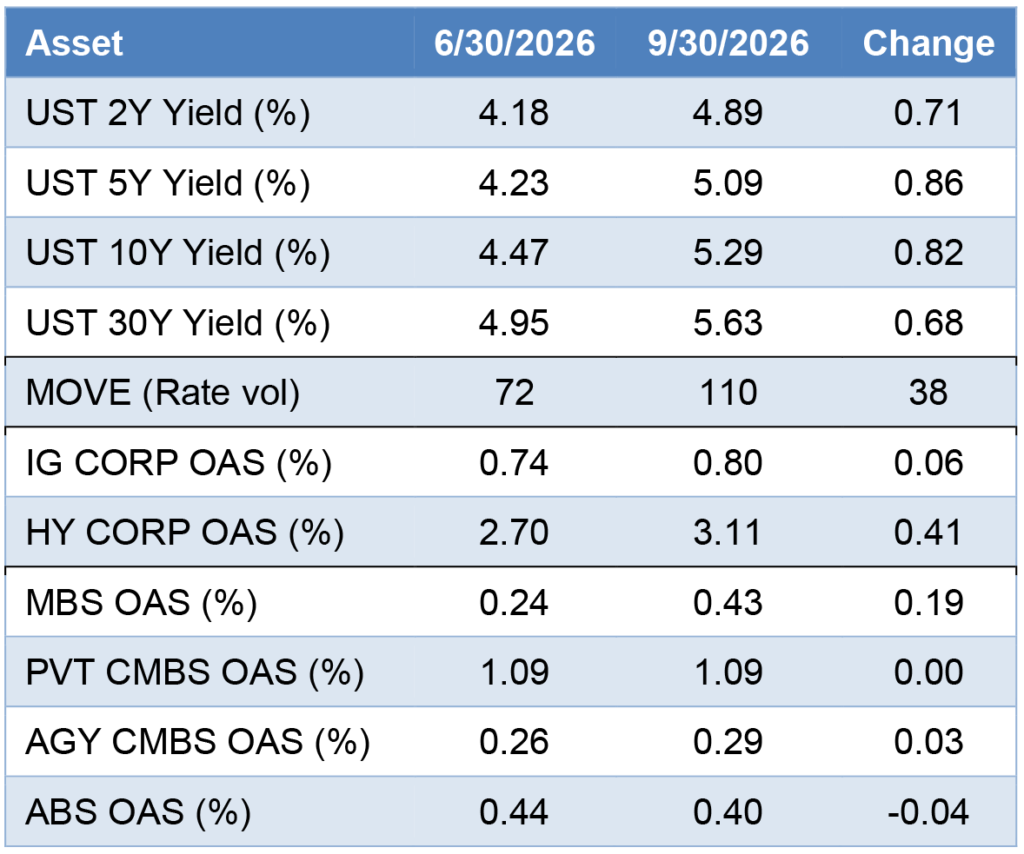
Rising rates and volatility have done most of the damage since June. Rates across the curve from the 2- to the 30-year have moved between 68 bp and 86 bp (Exhibit 4). Option- adjusted spreads on vol-sensitive MBS widened 19 bp through the quarter and spreads on high yield debt widened 41 bp, suggesting investor appetite for negative convexity dropped sharply.
Exhibit 4: Higher rates, higher vol, mostly wider spreads
Source: Bloomberg, Santander US Capital Markets
If there’s a useful lesson from the last quarter of performance in US fixed income, it may be that positioning in quality credit spreads is among the better risk-return tradeoffs. All credit is likely to be challenged by higher rates, but investment grade corporate and structured credit have good fundamentals and good supply-and-demand balance—outside of tech debt. Shorter duration looks better than longer. Quality credits look better than weaker.
* * *
The view in rates
The market is pricing another 25 bp of Fed tightening by December and then 58 bp more—for a total of 83 bp—before the end of 2027. The Fed dots in September showed a rise in expected inflation, unemployment above equilibrium and an economy running above its potential. Rates have reflected these concerns across the curve.
A break in the AI rally could hit credit and the broader economy and lead recession to drag rates lower, but that possibility looks remote. The AI build seems almost immune to higher rates for now. The first signs of interest rate sensitivity in tech are likely to come in the high yield and leveraged loan markets, where interest expense is a much bigger part of the cost structure. We’re not seeing it yet.
Apart from the AI rally, the market is clearly concerned about the impact of higher rates on other parts of the economy—housing, automotive, other rate-sensitive sectors. The question is the level of rates where those sectors start to noticeably slow.
Key market levels:
- Three-month term SOFR traded Friday at 405 bp, down 2 bp in a week
- The 2-year Treasury note traded Friday at 4.82%, down 4 bp in a week. The 10-year note traded at 5.27%, up 9 bp in a week.
- The Treasury yield steepened sharply, with 2s10s at 45 bp, up by 14 bp on the week. The 5s30s finished the week at 57 bp, up 6 bp on the week.
- The 10-year inflation breakeven traded Friday at 236 bp, up 2 bp in a week. The 5-year, 5-year forward breakeven was 233 bp, up 4 bp. The 10-year real rate ended the week at 291 bp, up 9 bp.
The view in spreads
Higher volatility is dominating spreads with MBS widening sharply and credit weaker. Fundamentals have moved to the sidelines for now. The Bloomberg US investment-grade corporate bond index option-adjusted spread traded Friday at 83 bp, wider by 5 bp in the last week. Nominal par 30-year MBS spreads to a blend of 5- and 10-year Treasury yields were 126 bp, wider by 8 bp. Par 30-year MBS Treasury option-adjusted spreads closed at 43 bp, wider by 6 bp in the last week.
The view in credit
Persistent high rates should put pressure on more leveraged balance sheets. Large companies have healthier balance sheets than smaller ones. Middle- and higher-income consumers also carry relatively little debt and have strong liquidity and wealth. Bank lending to nonbank financial institutions, including private debt funds and business development companies, continues to grow. Credit measures for nonbank financial lending remain stronger than those for traditional bank lending, such as commercial and industrial loans.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.