By the Numbers
Vantage score should have little effect on MBS valuation
This material is a Marketing Communication and does not constitute Independent Investment Research.
Fannie Mae and Freddie Mac this week started allowing all lenders to deliver loans using VantageScore 4.0 as an alternative to the classic FICO score. VantageScores on average are higher than classic FICO scores, so the GSEs are using a straightforward adjustment to determine pricing for loans delivered with VantageScore. MBS market participants should find that loans scored with either model have similar prepayment behavior after adjusting for the typical higher levels reporting by VantageScore.
The average VantageScore 4.0 (VS4) was 9 points higher than its Classic FICO score for loans originated between January 2023 and September 2025 and delivered to Fannie Mae (Exhibit 1). The table groups loans into FICO and LTV buckets that match how the GSEs price loans. The difference varies across these groups; in many buckets the difference ranges from 15 points to 20 points.
Exhibit 1. Average difference between VantageScore 4.0 and Classic FICO score
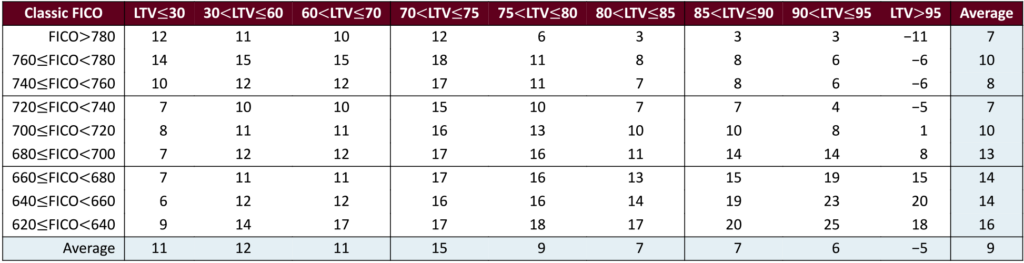
Origination from January 2023 through September 2025.
Source: Fannie Mae, Santander US Capital Markets.
The GSEs made the simple assumption that VantageScore is equivalent to a loan with a 20 point lower Classic FICO. For example, a borrower with 700 FICO score and a 75 LTV loan would be charged a 1.25% upfront fee. A borrower with a 720 VantageScore 4.0 and 75 LTV would also be charged 1.25%. This adjustment is close to the difference for lower credit borrowers that are charged higher LLPAs. It also aligns perfectly with the 20-point FICO buckets the GSEs use to price loans, which makes it simple for investors to identify scores that are charged the same fee. Fannie Mae’s loan-level price adjustment (LLPA) matrix is available here and Freddie Mac’s credit fees are here.
Loans have similar prepayment behavior regardless of which score is used, after incorporating the 20-point adjustment (Exhibit 2). The graph shows S-curves for low credit score specified pools formed by grouping two different ways: (1) loans with FICO<700, or (2) loans with VS4<720. The VS4 loans do prepay a little faster in-the-money and a little slower out-of-the-money, but the difference is small.
Exhibit 2. Prepayment S-curves for borrowers with low credit scores
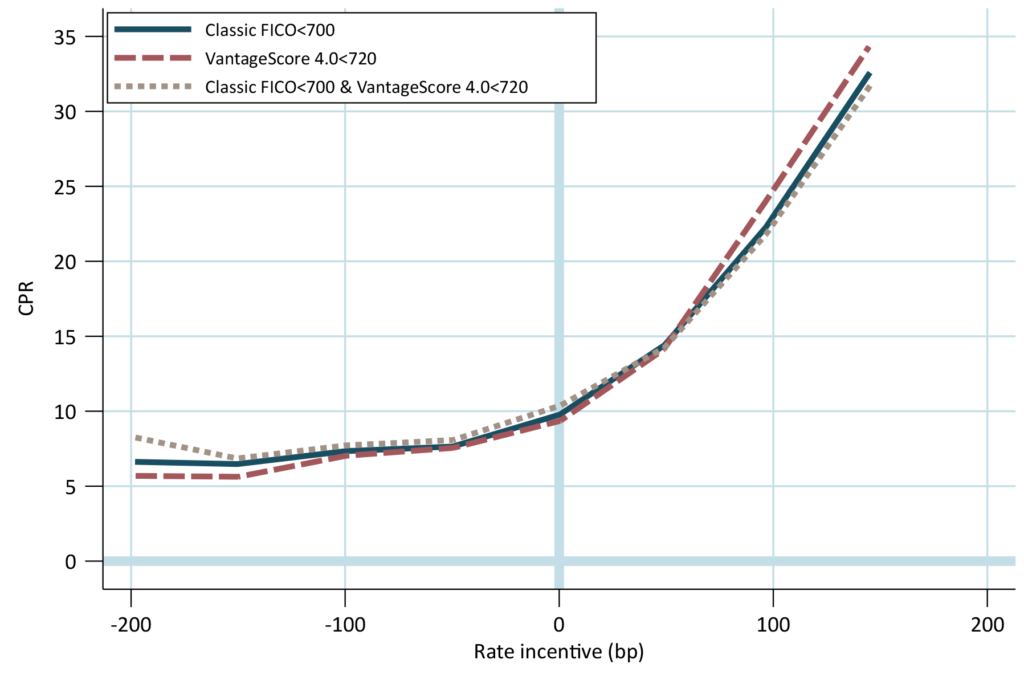
Fixed-rate 30-year loans, owner occupied, original LTV≤80, 6 to 24 months seasoned, $400,000 to $600,000 original loan size. Performance from January 2023 through August 2026.
Source: Fannie Mae, Santander US Capital Markets.
The graph also includes a third line that represents only loans that have low credit scores using both models. This is often known as “Lender’s Choice”—the lender runs both scores and can use the higher score to sell the loan with possibly a lower LLPA. In that environment, only loans that have low scores in both models—FICO<700 and VS4<720—would be put into a specified pool. This group has slightly higher convexity than either of the single-score S-curves, prepaying the slowest in-the-money and the fastest out-of-the-money. Therefore, convexity could improve a bit for low credit score pools.
S-curves are very similar for the high credit score population (Exhibit 3). One curve is Classic FICO≥700, another is VS4≥720, and the third is loans that meet either (or both) of those criteria. The S-curves are hard to distinguish; the VS4 S-curve is slightly faster than Classic FICO in-the-money, which suggests that model may be differentiating prepayment behavior that Classic FICO doesn’t pick up. But the difference is small.
Exhibit 3. Prepayment S-curves for borrowers with at least one high credit score
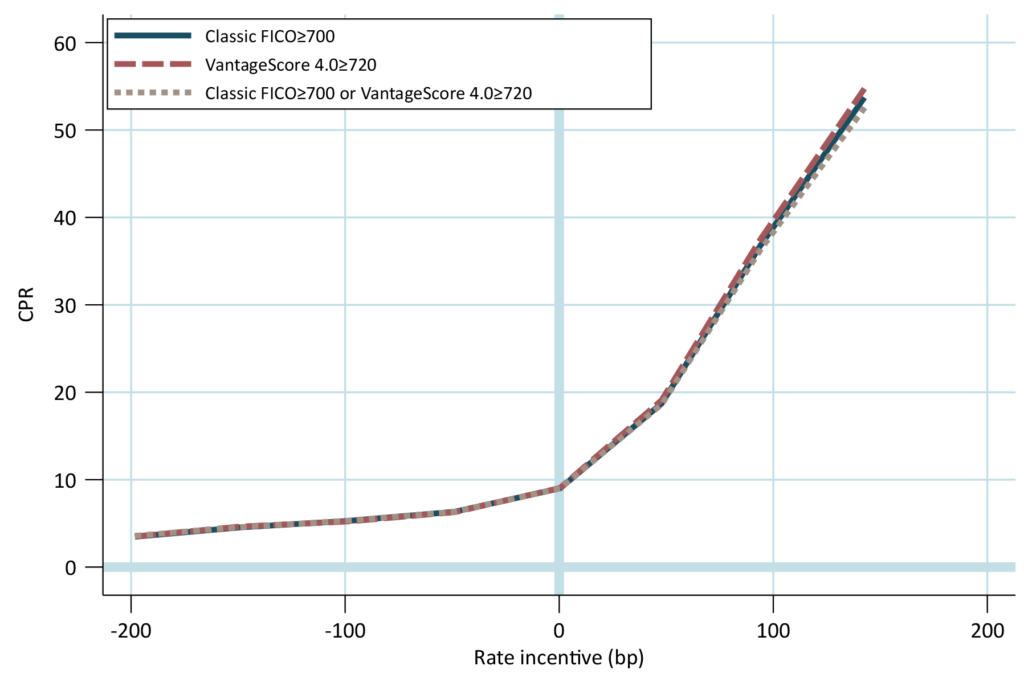
Fixed-rate 30-year loans, owner occupied, original LTV≤80, 6 to 24 months seasoned, $400,000 to $600,000 original loan size. Performance from January 2023 through August 2026.
Source: Fannie Mae, Santander US Capital Markets.
Interestingly, S-curve for loans that could have a high score in both models or only one model prepay the slowest when in-the-money, although the difference is very small. The reason is that the borrowers that have one good score, but not two good scores, have slightly better convexity than the loans with two good scores. If a lender uses one score then some of these borrowers would have been put into a specified pool. By using both models, these borrowers are delivered into a generic pool. That improves the convexity of generic pools. Total convexity in the market doesn’t change because specified pool issuance would drop and generic pool issuance would increase.
Lender’s choice assumes that delivering using the higher score (after the 20-point adjustment) is best execution, since that will always result in the lowest LLPA. However, for loans near the specified pooling threshold, there could be occasions that using the lower score makes sense. For example, the current pay-up for 2026 vintage, low FICO, 6.0% pools is $0-19+, according to Bloomberg’s BVAL. A 75 LTV loan with a 690 FICO and 730 VS4 would save 0.375%, or $0-12, on LLPAs by using the Vantage score. Delivering into a specified pool using the lower FICO score would net $0-07+ because the pay-up is higher than the LLPA difference.
Introducing VS4 does mean that some borrowers may receive a VantageScore that is over 20 points higher than the current FICO score (Exhibit 4). This shows the distribution of VantageScores received by borrowers with FICO scores between 680 and 700. Many borrowers received VantageScores over 720, which would often lead to a lower LLPA. So, some borrowers may find their refinance cost is lower with the introduction of VS4. But many borrowers also would receive comparable or lower VantageScore.
Exhibit 4. The relationship between the two scores is noisy
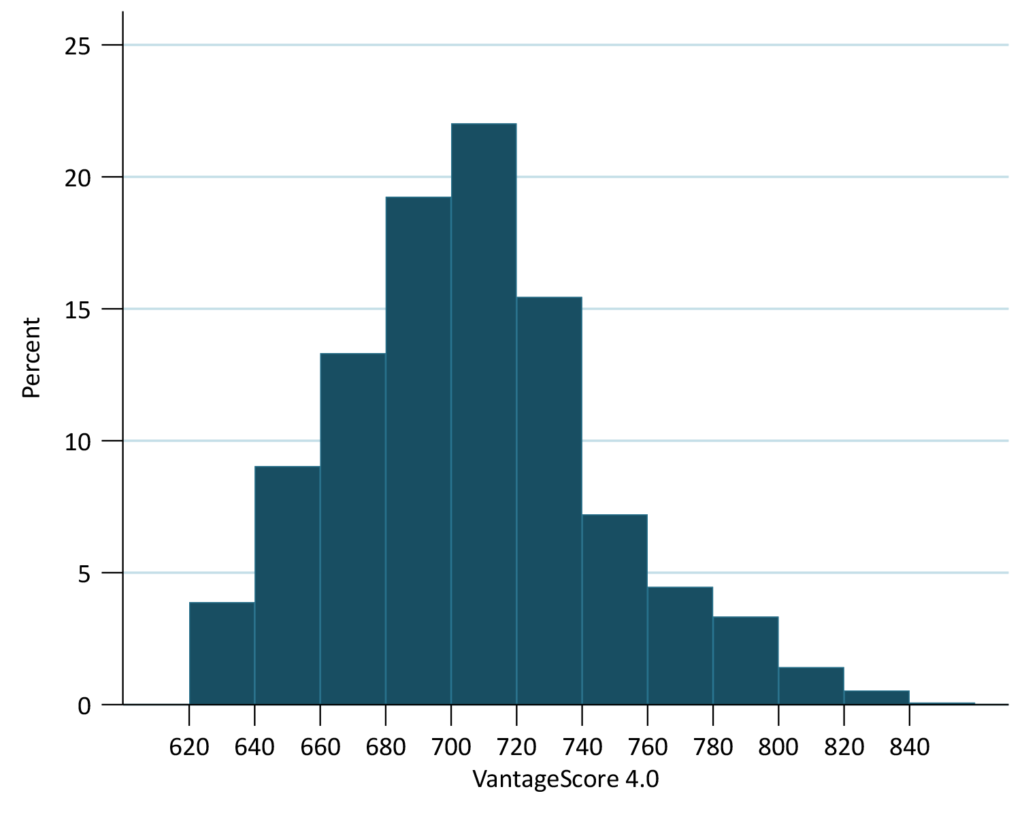
Loans with 700≤Classic FICO<720.
Source: Fannie Mae, Santander US Capital Markets.
More changes are coming, although it seems unlikely any will have big effect on MBS valuations. Fannie Mae and Freddie Mac are working towards authorizing use of the FICO 10T score. FHFA Director Pulte also posted that the GSEs will begin disclosing their internal credit metrics along with all three credit scores for MBS and CRT securitizations. More transparency is always welcome. Director Pulte also stated that Fannie and Freddie will explore allowing lenders to only pull credit scores from two credit bureaus and possibly even accept loans with no credit score for delivery. The FHA will start accepting VS4 and FICO 10T on January 1, 2027.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.