By the Numbers
Relative value skews toward agency loans in private-label MBS
This material is a Marketing Communication and does not constitute Independent Investment Research.
A growing number of investors likely see better value owning agency exposure in private-label form. Despite the recent decline in specified-pool payups, private-label pass-throughs, particularly those backed by investor loans, continue to deliver attractive relative value for investors willing to give up the liquidity the agency market provides.
Valuations on specified pools have taken a hit recently as the combined effect of rising benchmark yields and persistently low interest-rate volatility has weighed on payups. At the same time, issuance of private-label deals backed by agency-eligible collateral has increased substantially. Depressed specified-pool valuations coupled with heavier private-label supply would imply that agencies should offer better relative value. Despite that, owning the exposure in private-label form may still look better.
Are the exposures really the same?
Gauging relative value starts with whether the exposures are truly like for like. The somewhat obvious answer is no. Moving away from TBA delivery is a major concession in both liquidity and the price at which the asset can be floored. Other structural differences exist as well. While both assets analyzed are nominally pass-through classes, the private-label exposure is more sequential in nature. The bonds that provide credit support to senior classes are locked out from prepayments for a period, making the senior classes more leveraged to those prepayments.
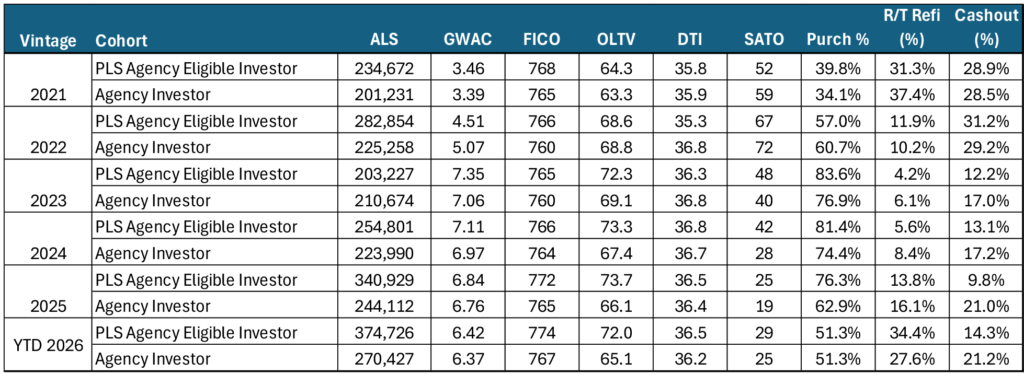
Other differences exist as well. Loans delivered into private-label execution consistently carry substantially higher average loan balances and higher LTVs. They tend to carry higher rates and more SATO despite substantially lower concentrations of cash-out refinances (Exhibit 1).
Exhibit 1: Comparing investor loans in conventional and private-label execution
Source: Santander US Capital Markets, CoreLogic LP
Higher-balance and higher-LTV pools with lower cash-out concentrations make sense within the private-label execution framework. Fixed costs associated with default, foreclosure and liquidation translate into lower fixed loss severities on larger loans. Conventional LTV-based pricing adjustments for investor loans are somewhat blunt, leaving room for more refined private-label pricing of credit enhancement. Conversely, cash-out refinances generally require substantially more credit enhancement than comparable purchase or rate-and-term refinance loans, making agency execution a more viable channel.
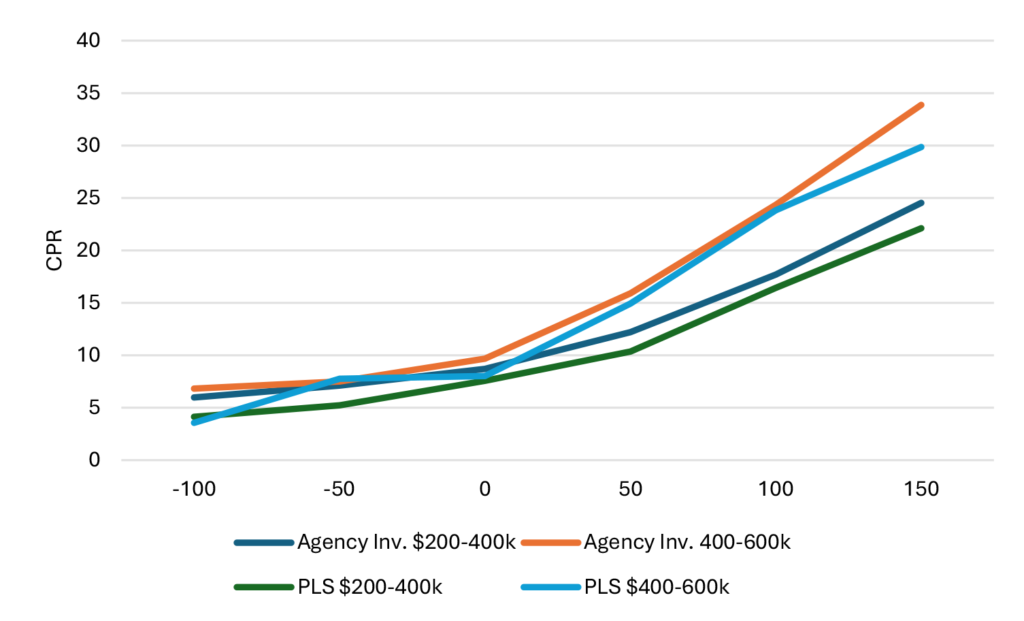
Higher average balances do not appear to be causing greater negative convexity in private-label trusts. Comparing S-curves for loans with similar balances in private-label trusts and agency pools shows that at-the-money speeds are actually slightly slower in private-label execution. Private-label loans prepay 2 to 4 CPR slower when deeply in the money. Slower in-the-money speeds on private-label loans may be attributable to servicing transfers from agency servicers, which are likely more efficient at refinancing these loans, to less efficient private-label servicers. That is despite the fact that these borrowers could just as easily refinance into another conforming loan (Exhibit 2).
Exhibit 2: Comparing S-curves on agency and PLS investor loans
Source: Santander US Capital Markets, CoreLogic LP
Measuring relative value with a constant OAS methodology
One way to establish a level playing field for relative-value analysis is to use an “equal OAS” methodology because OAS accounts for differences in structure and collateral. The analysis compares 5.5% and 6.0% coupon pass-throughs in private-label and specified-pool form. One important distinction between the two exposures is that coupon options in the private-label market are stripped from the same collateral group, while specified pools carry different gross WACs at different pass-through rates. The specified pools also have larger average loan balances.
The private-label 5.5% and 6.0% pass-throughs are priced 16/32 and 20/32 behind their respective TBA benchmarks. The specified pools are priced 0.5/32 and 6/32 above their TBA benchmarks. At these levels, the private-label pass-throughs offer 41 basis points and 54 basis points of OAS, while the agency pools deliver 18 basis points and 17 basis points, respectively (Exhibit 3).
Exhibit 3: An OAS comparison of PLS and agency exposures
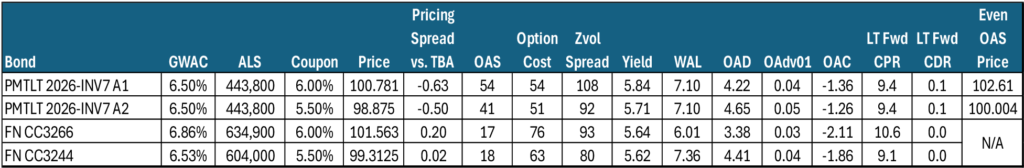
Note: YieldBook uses different prepayment models for agency investor loans and agency-eligible investor loans securitized in private-label MBS. This may make OAS values and calculations that use the OAS values non-comparable.
Source: Santander US Capital Markets, YieldBook
Running the private-label pass-throughs to the same OAS as their agency counterparts pushes their theoretical values not only above TBA but also above the comparable specified pools. In reality, this pricing construct would never materialize for a couple of reasons. First, pools, even in the agency market, rarely trade at or near 100% of their theoretical value under a constant-OAS methodology. Second, and potentially more important, the market should and will demand a concession for the diminished liquidity associated with private-label execution.
However, the theoretical value does carry some weight. While private-label execution historically has skewed toward larger loans, that may become less pervasive as all loans get bigger, making fixed severities associated with liquidating those loans less important. In the examples above, the average loan size backing the PLS trust is roughly $150,000 to $200,000 smaller than that of the comparable pools, likely translating into more OAS on the private-label bonds. Additionally, the 6.0% private-label pass-through has substantially less option cost than the comparable pool because of its substantially lower gross WAC.
Accounting for credit and liquidity
While the equal-OAS methodology accounts for differences in structure and convexity, it may not adequately account for potential credit risk in PLS and certainly does not account for the liquidity give-up in PLS relative to specified pools. Regarding credit risk, all exposures are fairly pristine, with projected CDRs near zero. Assuming no material concession for credit, the analysis comes down to liquidity, which historically has been difficult to gauge. In periods of relatively muted volatility, investors appear to be more than adequately compensated to give up the liquidity associated with agency pools. In periods of elevated volatility, that may be less true.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.