By the Numbers
CLO Snapshot
This material is a Marketing Communication and does not constitute Independent Investment Research.
Quality CLO managers extended their winning track record in July against the leveraged loan market index and speculative peers. And ‘AAA’ through ‘A’ CLO debt delivered solid returns with relatively low volatility. August already looks busy, with ‘BBB’ and ‘BB’ spreads tightening and projected equity yields rising.
The highlights from July:
- RETURNS AND RV: ‘AAA’ through ‘A’ trade tight; ‘BBB’ and ‘BB’ trade wide
- REFI AND CREDIT RISK: Refi risk remains high; credit improves
- MANAGER PERFORMANCE: Quality managers beat the market by 9 bp
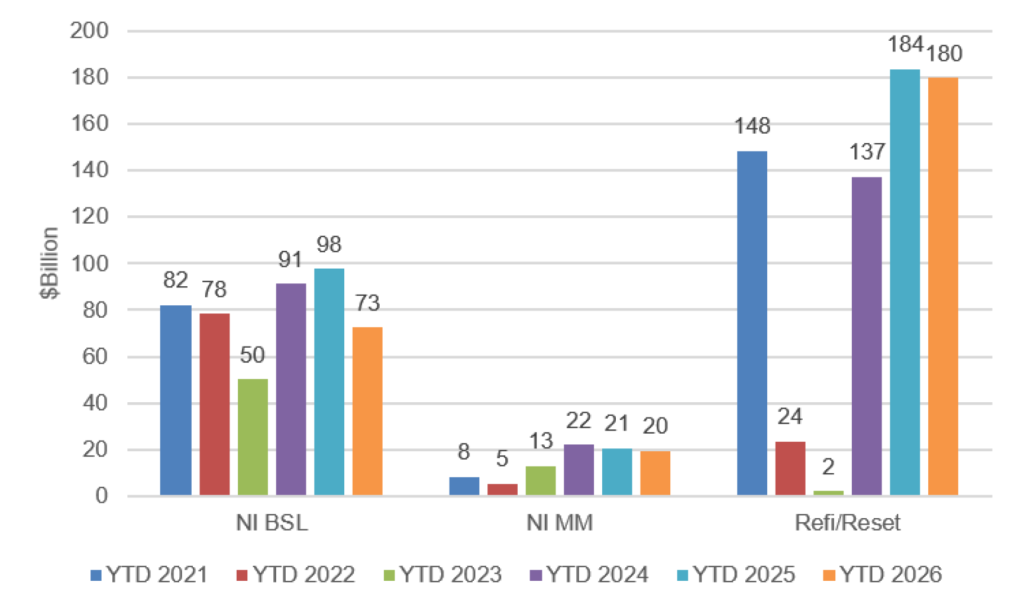
- PRIMARY FLOWS: Refi/reset still dominates YTD2026 primary flow
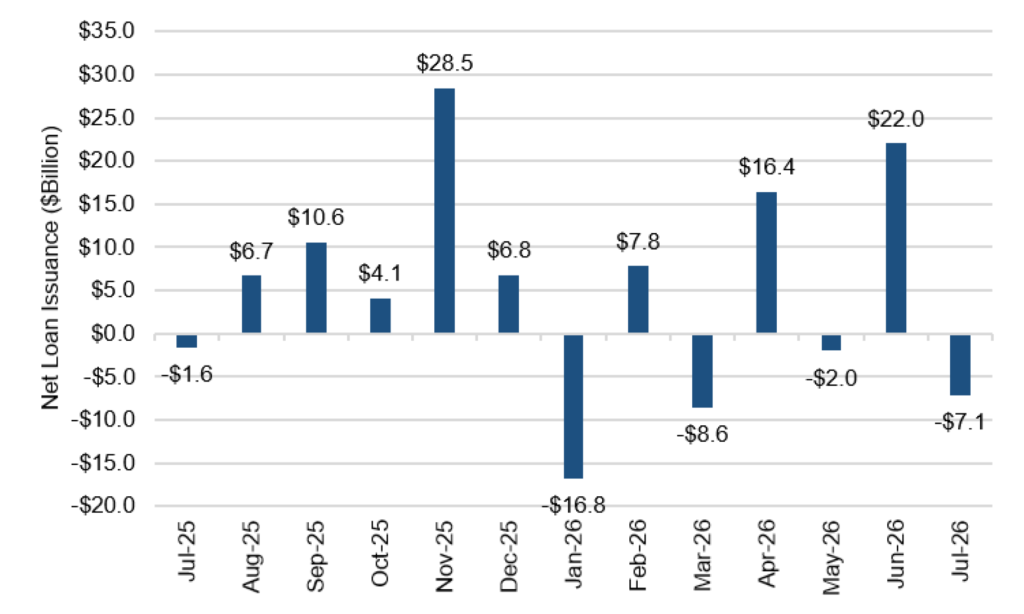
- LOAN MARKETS: Net loan supply falls in July; only $12B net YTD
RETURNS AND RV
CLO returns are similar across ratings in July
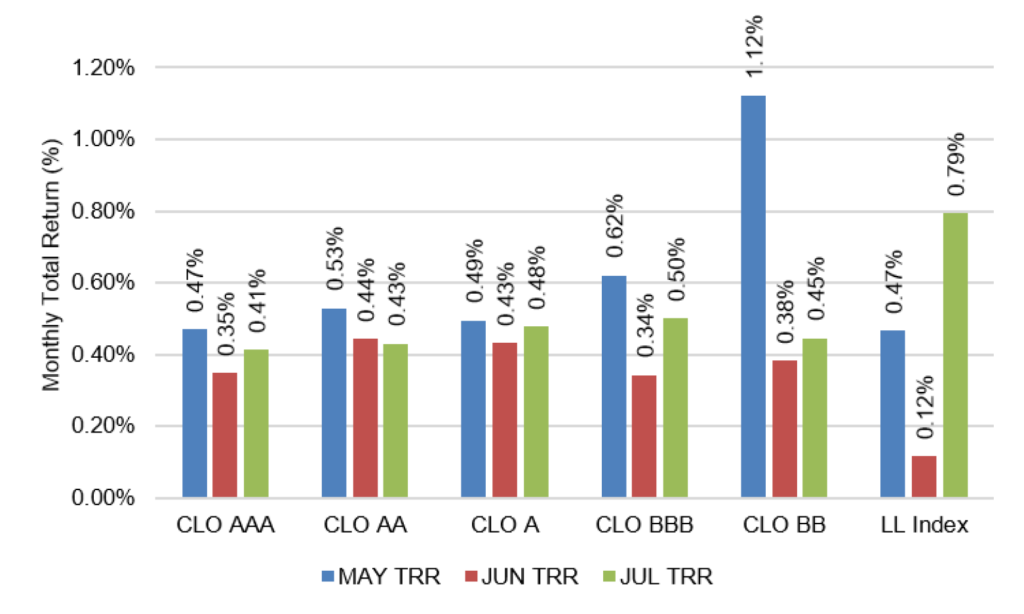
Note: Returns through 7/31/26.
Sources: Palmer Square, Bloomberg and Santander US Capital Markets.
Top-of-stack CLOs deliver relatively high returns per unit of risk over the past 12 months
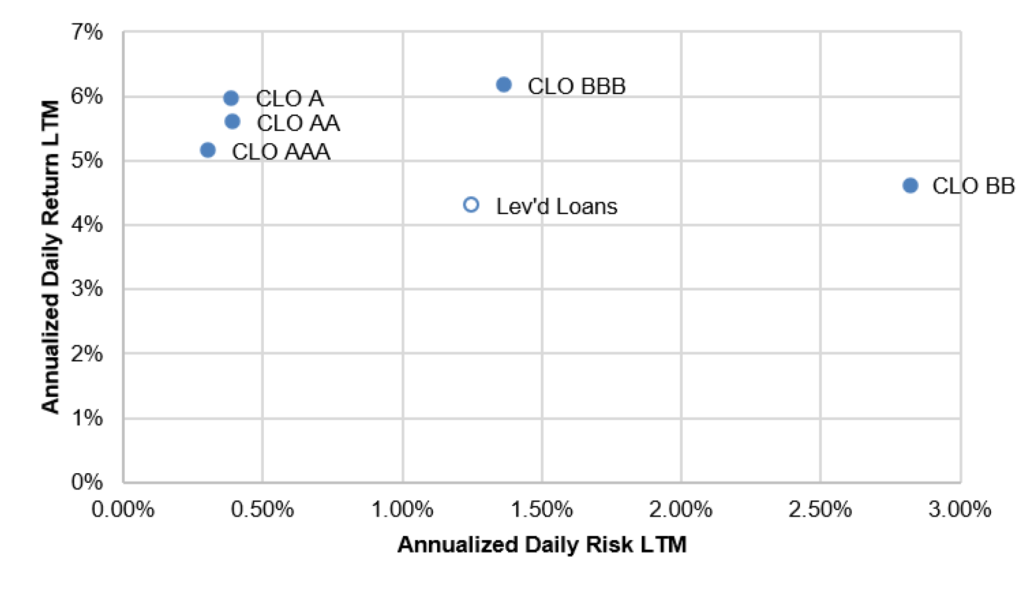
Note: Returns from 7/31/25 through 7/31/26.
Sources: Palmer Square, Bloomberg and Santander US Capital Markets.
CLO discount margins widen in July: ‘AAA’ by 1 bp, ‘AA’ by 2 bp, ‘A’ by 1 bp, ‘BBB’ by 3 bp and ‘BB’ by 12 bp
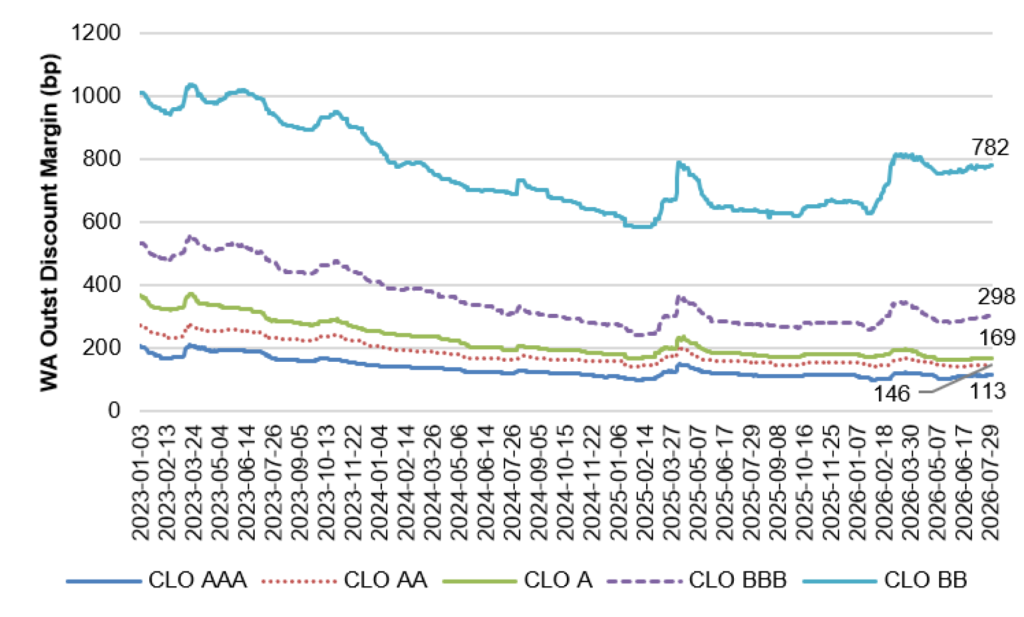
Note: Spreads to SOFR through 7/31/26 for the average outstanding class. New-issue spreads may differ.
Sources: Palmer Square, Bloomberg and Santander US Capital Markets.
CLO ‘BBB’ and ‘BB’ end July wide to their 1-year median DM; only ‘BB’ remains wide over longer periods
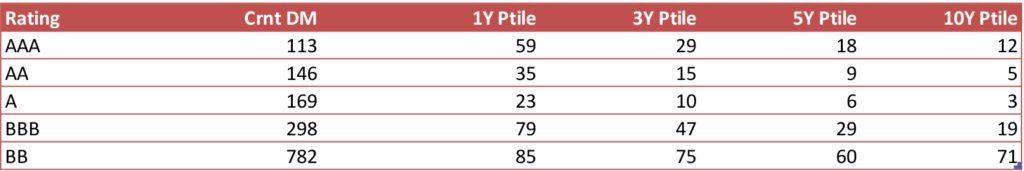
Note: A percentile rank of 100 is widest, 50 is median and 0 is tightest. Data show average DM to SOFR for outstanding debt.
Sources: Palmer Square, Bloomberg and Santander US Capital Markets.
CLO ‘BBB’ and ‘BB’ also trade wide to their 1-year median spread to corporate debt; ‘BB’ remains wide over longer periods
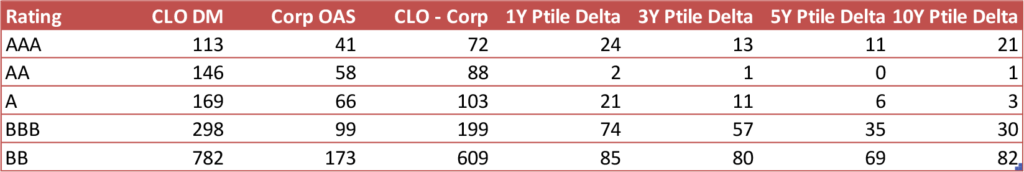
Note: A percentile rank of 100 is widest, 50 is median and 0 is tightest. Data show average DM to SOFR for outstanding debt.
Sources: ICE BofA Corporate Indices and Santander US Capital Markets.
New BSL CLO spreads price in a tight band from ‘AAA’ through ‘A’
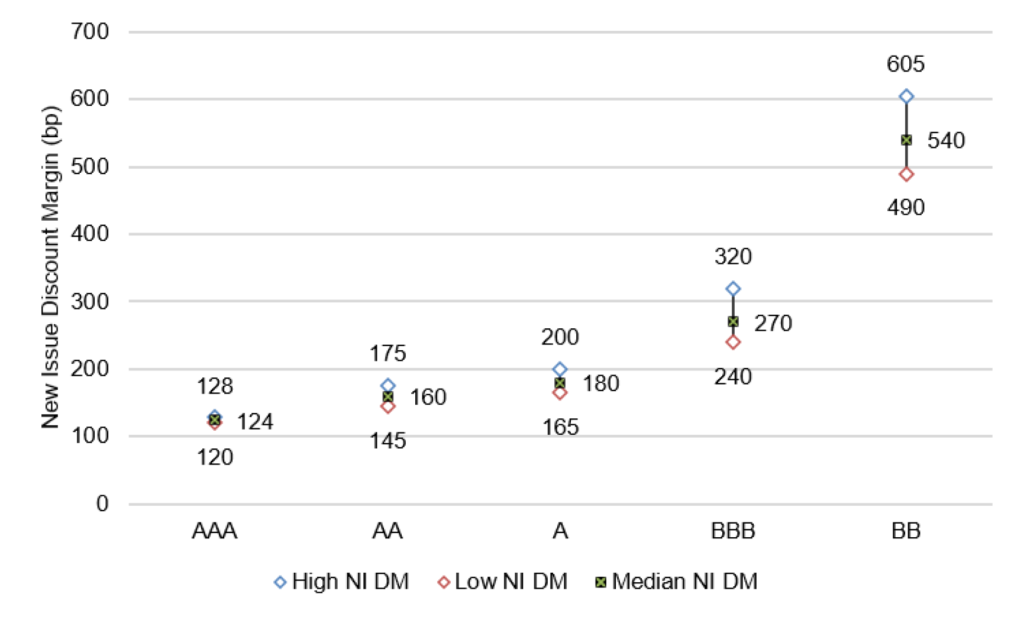
Note: Based on 19 deals. Monthly spread changes may reflect shifts in manager and deal structure mix.
Source: Santander US Capital Markets.
Secondary BSL spreads trade tight to primary from ‘AAA’ through ‘A’ and wide to primary for ‘BBB’ and ‘BB’
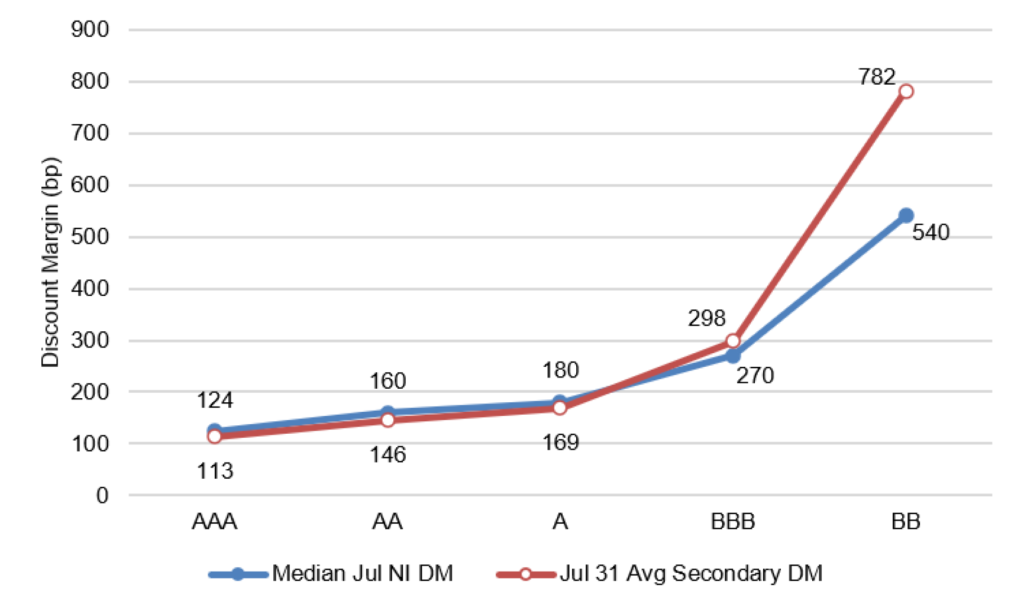
Note: NI DMs reflect markets throughout the month and may include deals priced weeks earlier; secondary DMs reflect month-end markets. The spreads are not directly comparable.
Source: Santander US Capital Markets.
New middle market CLO spreads trade in a wider band
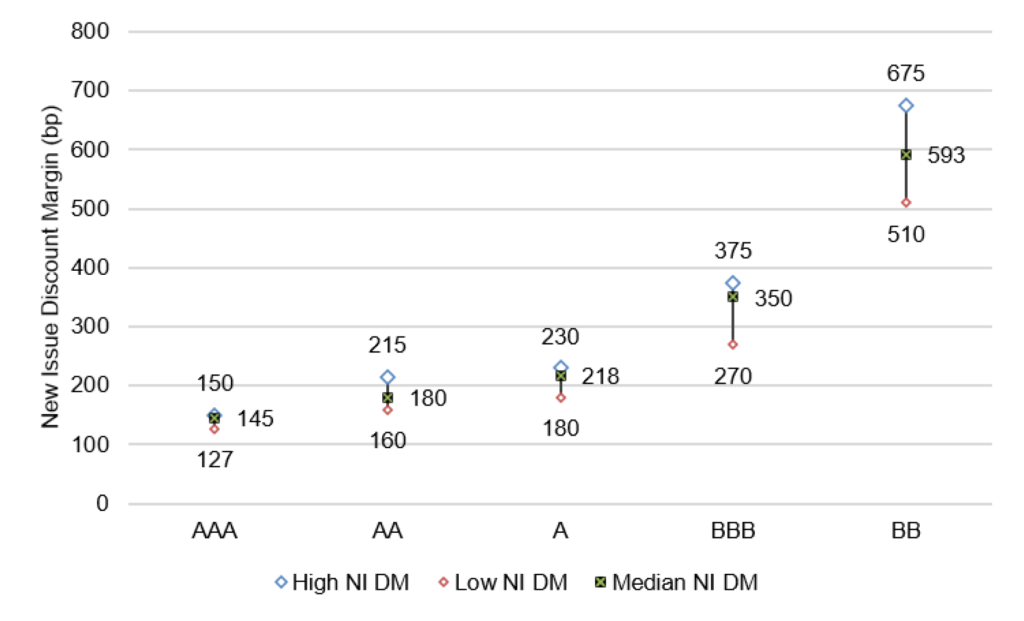
Note: Based on two to five deals. Monthly spread changes may reflect shifts in manager and structure mix.
Sources: Palmer Square, Bloomberg and Santander US Capital Markets.
A narrow gap in spreads on new BSL and middle market CLOs
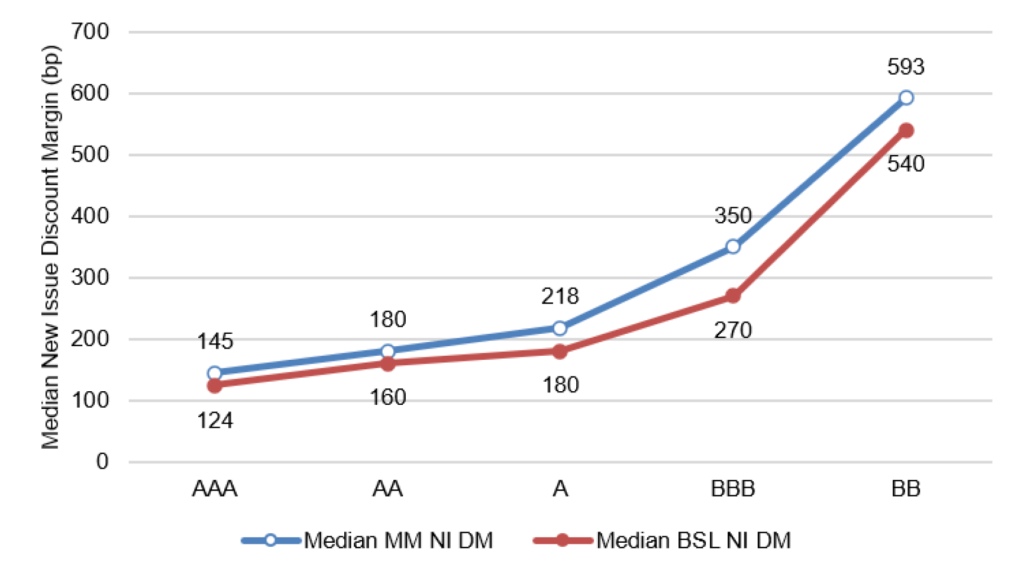
Note: Based on median BSL and middle market spreads.
Source: Santander US Capital Markets.
REFI AND CREDIT RISK
Of 524 CLOs within six months of first call, 74% have 0 bp or more of refi incentive at July’s median NI ‘AAA’ DM
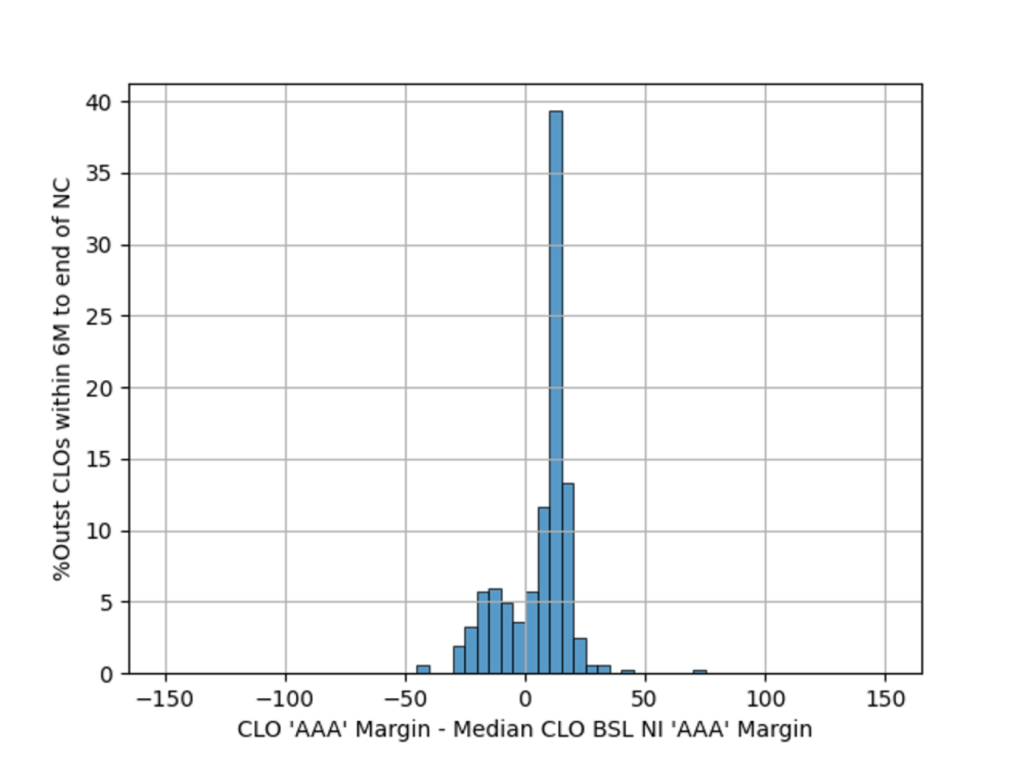
Source: Santander US Capital Markets.
Credit: Junior OC cushions rise in recent months
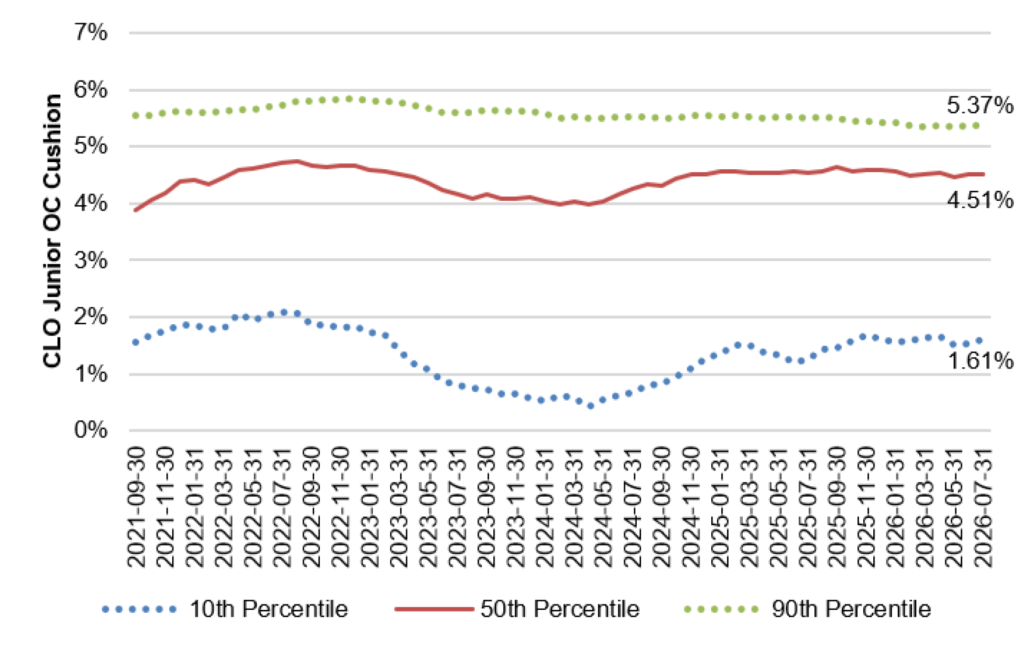
Source: INTEX, Santander US Capital Markets.
Credit: Median loan spreads remain flat
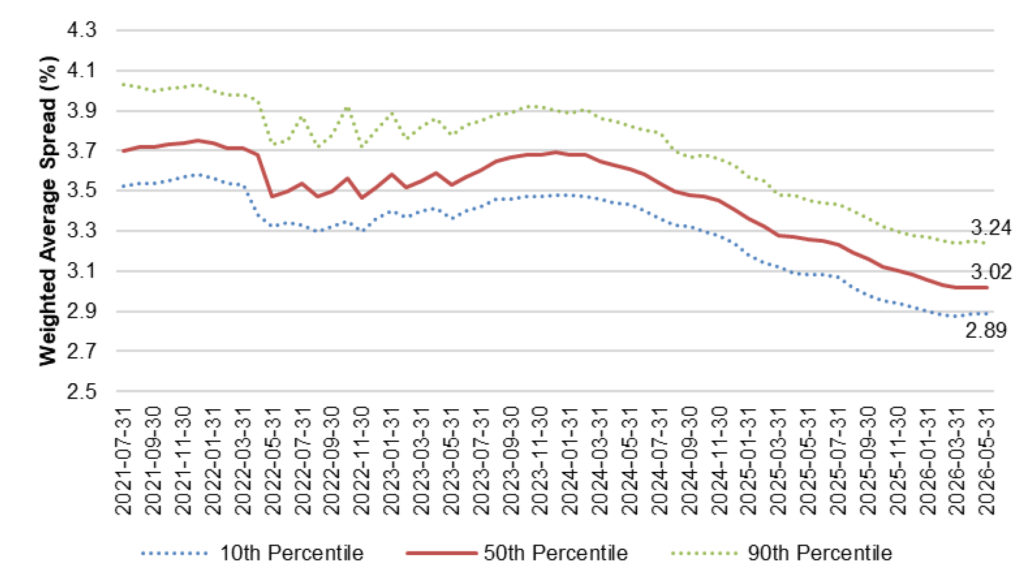
Source: INTEX, Santander US Capital Markets.
Credit: WARFs continue to fall
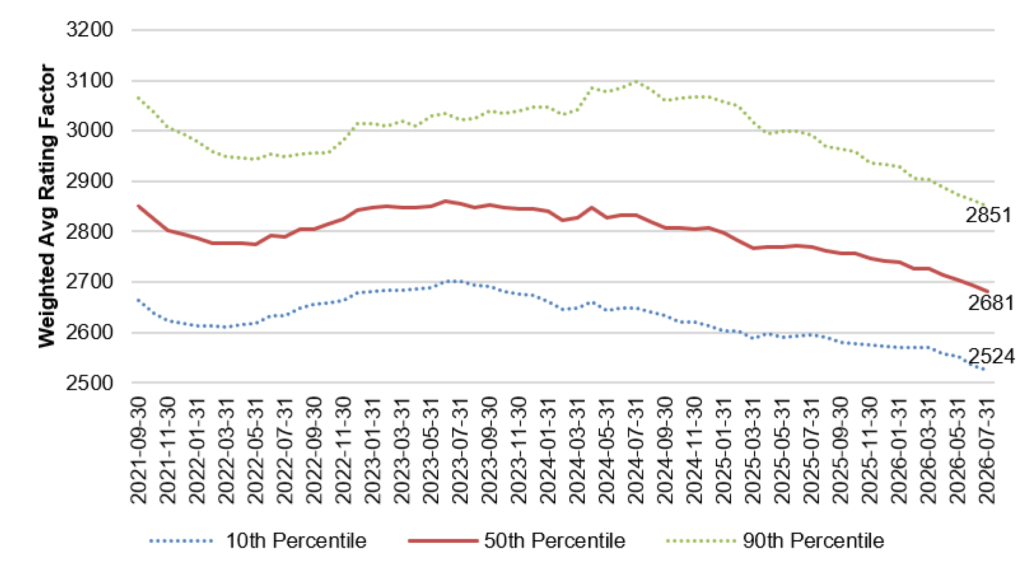
Source: INTEX, Santander US Capital Markets.
Credit: Diversity scores rise
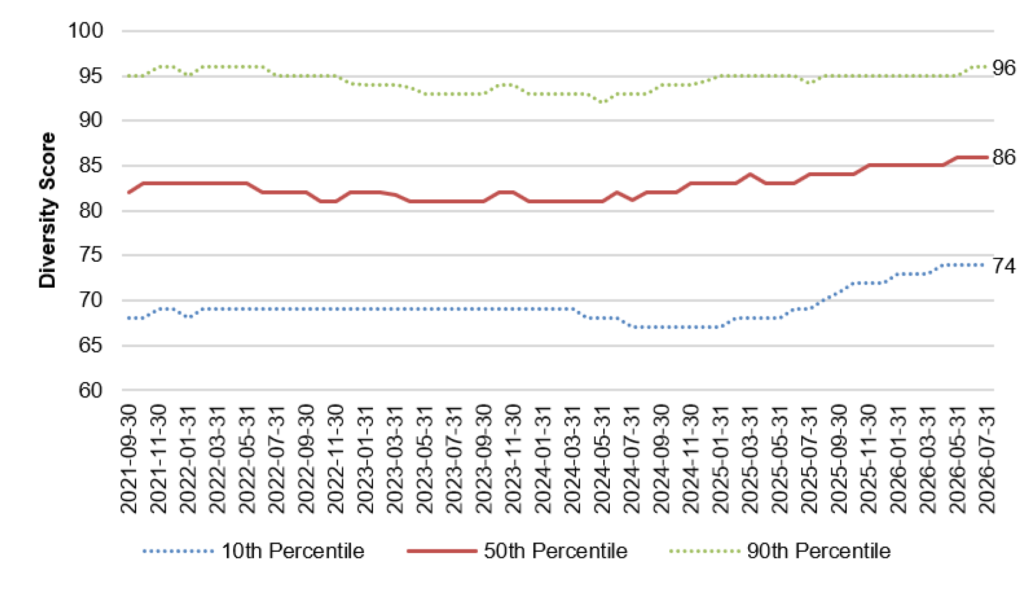
Source: INTEX, Santander US Capital Markets.
Loan weighted average lives lengthen slightly
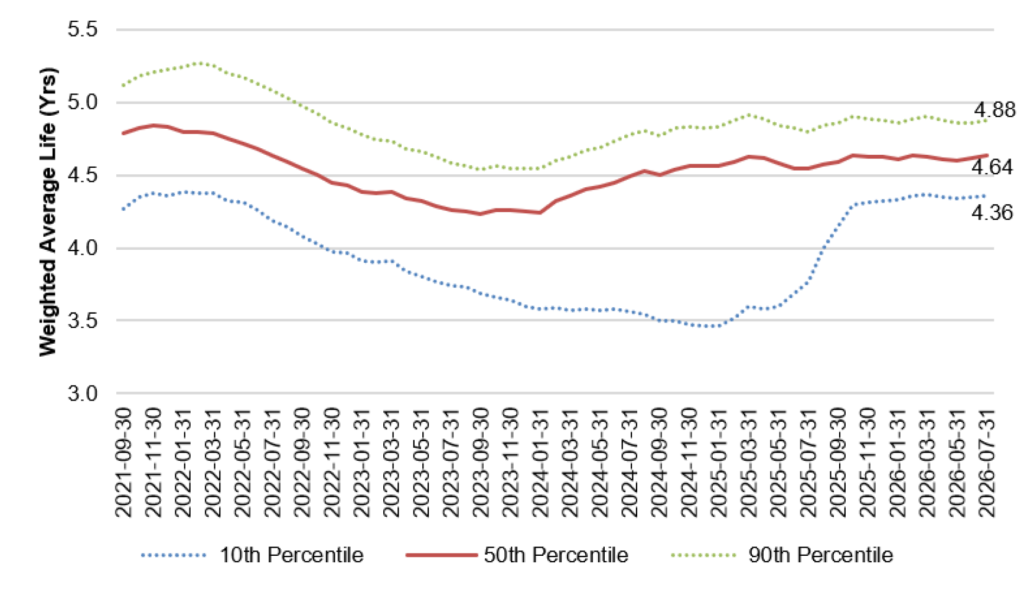
Source: INTEX, Santander US Capital Markets.
MANAGER PERFORMANCE
Quality portfolios beat the Morningstar/LSTA loan index risk-adjusted return by 9 bp through July and speculative peers by 11 bp
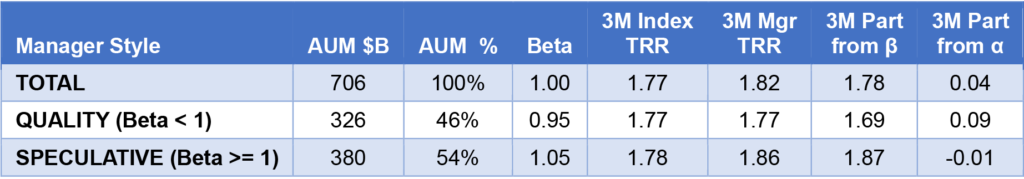
Note: Performance covers the three monthly reporting dates before Jul 20, 2026, for managers tracked by Santander US Capital Markets with at least five deals issued since Jan 1, 2011. Attribution starts with the calculated total return of each CLO’s leveraged loan portfolio for the 3-month reporting period ending on the stated date. Reporting periods may vary among CLOs, including those managed on the same platform. Each period is matched with the same period in the Morningstar/LSTA Leveraged Loan Index. For deals with at least 18 months of performance history since pricing and no apparent cash-flow errors, the analysis calculates beta and multiplies it by the index return to estimate return from broad market performance. If beta cannot be calculated, the analysis uses the average beta of the manager’s deals, weighted by average principal balance. The difference between beta-attributed and actual performance is manager alpha.
Sources: INTEX, Markit and Santander US Capital Markets LLC.
Shenkman, Black Diamond, TCW, Crescent and Kennedy Lewis lead the Top 25 alpha producers for the three months through July
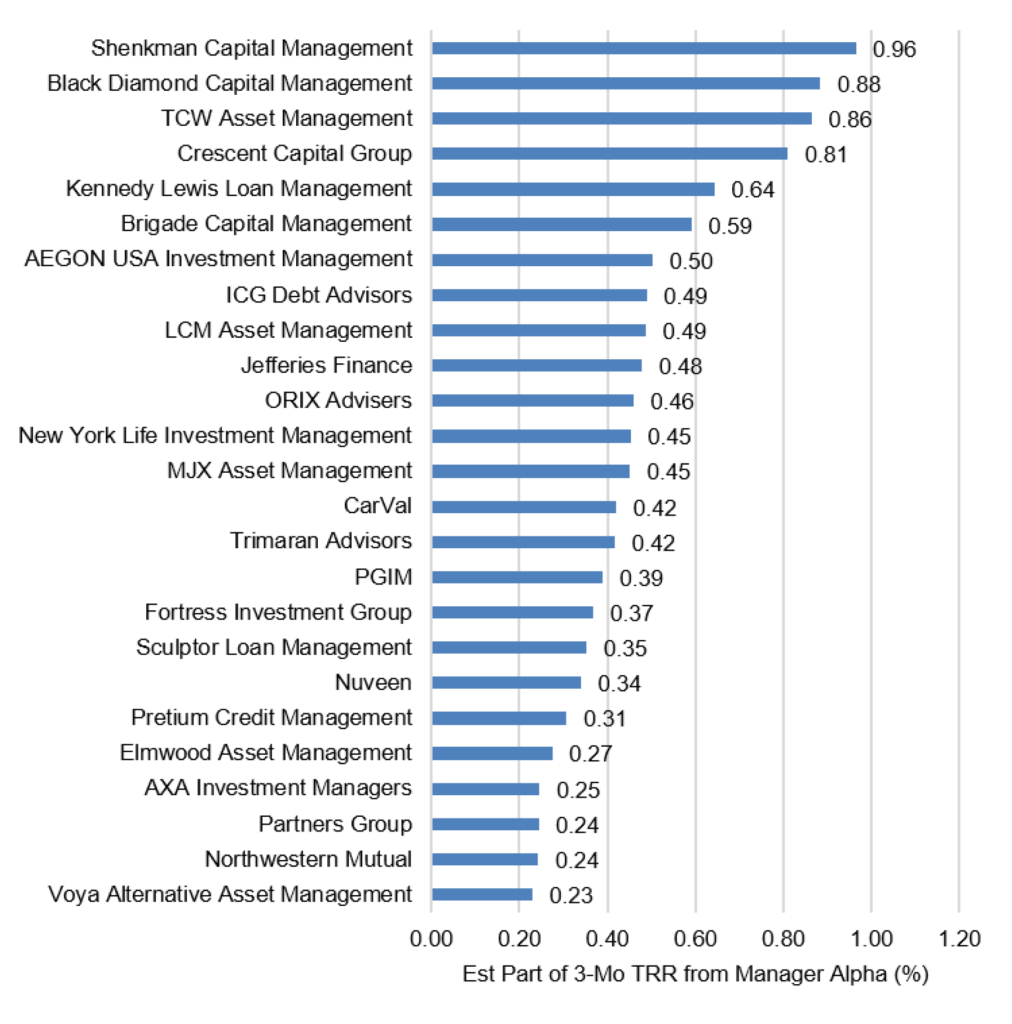
Note: See note for table above.
Source: INTEX, Santander US Capital Markets.
Find detailed CLO manager analysis at US Portfolio Strategy.
PRIMARY FLOWS
BSL refi/reset still dominates the YTD2026 primary market
Source: Bloomberg, Santander US Capital Markets
LOAN MARKETS
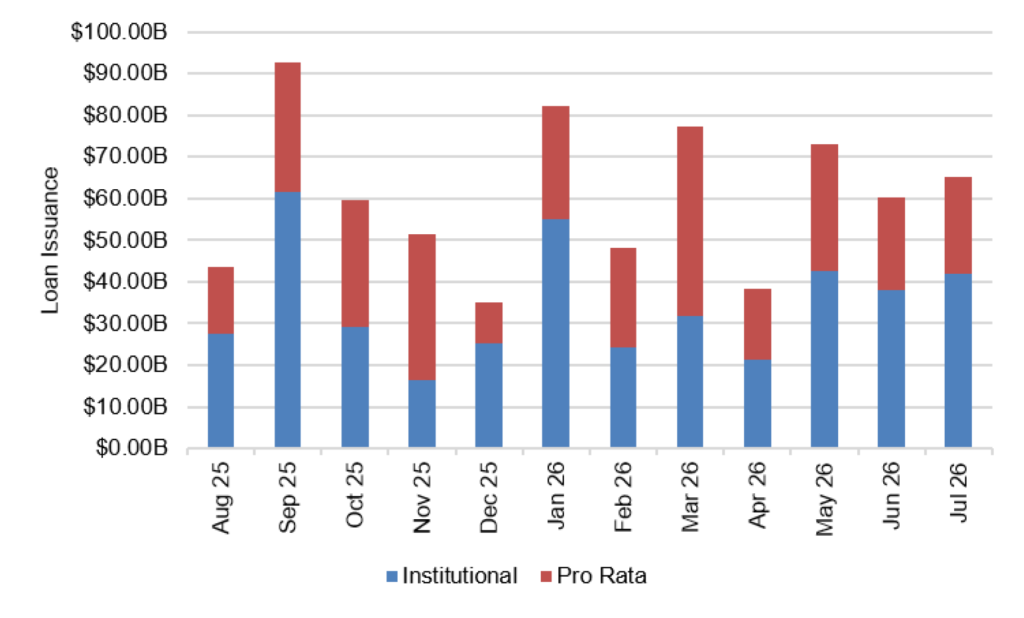
Gross leveraged loan issuance tops $65B in July
Source: PitchBook | LCD Leveraged Loan Data US, Santander US Capital Markets
Net leveraged loan supply falls $7B, or 0.45%, in July, leaving the YTD total at $12B
Source: PitchBook | LCD US Leveraged Loan Index Factsheet, Santander US Capital Markets
Rolling 90-day yields on new ‘BB’ and ‘B’ loans hold steady through July
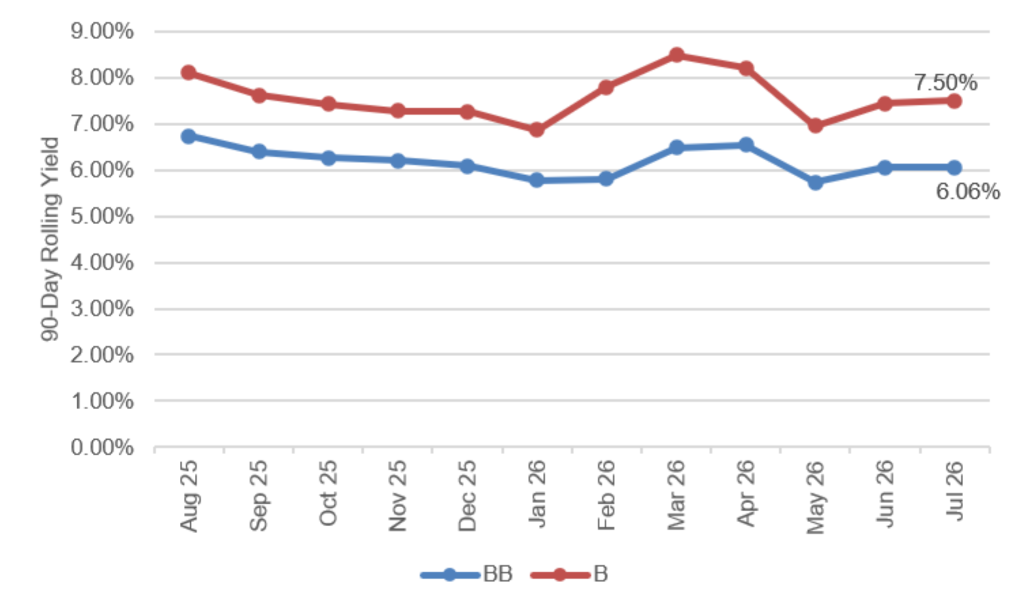
Note: Data show rolling 90-day yields.
Sources: PitchBook | LCD and Santander US Capital Markets.
Special thanks to Sophia Cui for key data analysis.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.