By the Numbers
GSE portfolios resume growth in June
This material is a Marketing Communication and does not constitute Independent Investment Research.
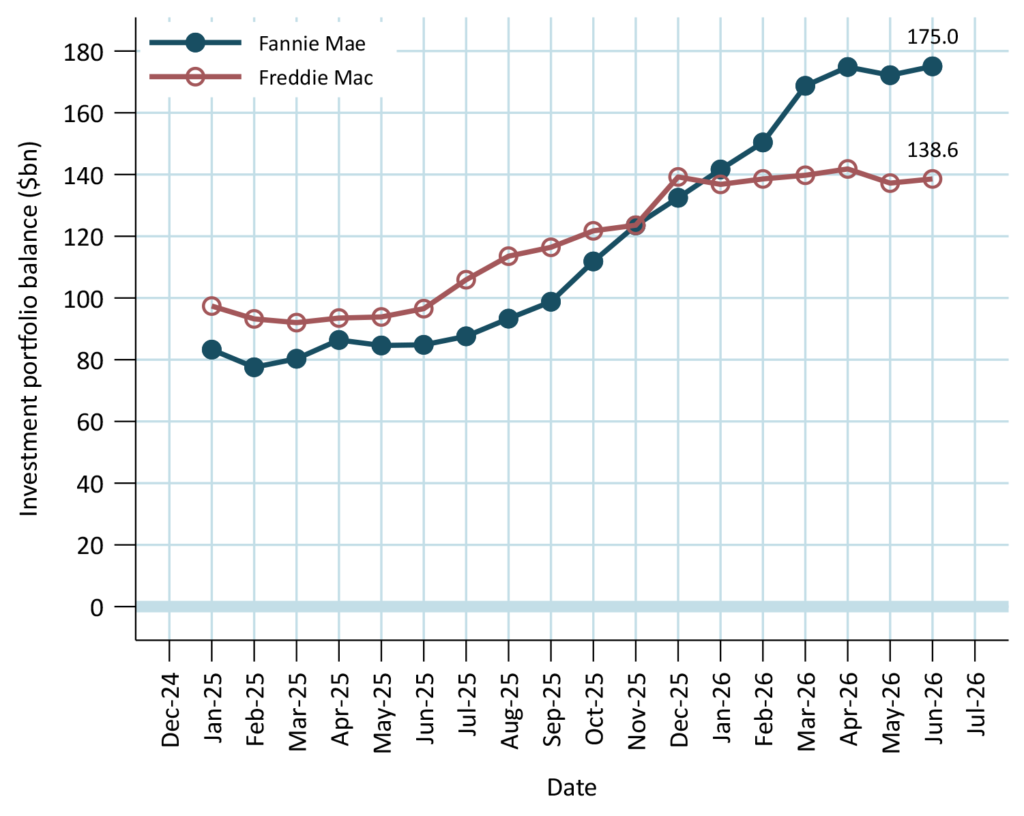
Fannie Mae’s and Freddie Mac’s retained mortgage portfolios grew in June, reversing some of May’s decline. Fannie Mae’s portfolio rose $2.9 billion to $175 billion, while Freddie Mac’s increased about $1.3 billion to $138.6 billion. They nevertheless ended the first half of 2026 on different paths, Fannie Mae expanding sharply with Freddie Mac staying near its year-end balance. Interest rate exposure rose again at both companies.
Fannie Mae’s June increase put its portfolio just above its March high and $42.6 billion above year-end (Exhibit 1). Freddie Mac’s rebound offset only part of its $4.6 billion May decline, leaving the portfolio little changed from $139.2 billion at the end of 2025. The combined balance rose to about $314 billion.
Exhibit 1. Both retained portfolios grew in June
Source: Fannie Mae, Freddie Mac, Santander US Capital Markets.
Fannie Mae’s larger year-to-date increase points to an active investment program. But uneven monthly purchases suggest it is not a steady, programmatic buyer. In its second-quarter 10-Q, Fannie Mae said first-half growth came mainly from agency MBS purchases after FHFA raised its investment limit in January. The purchases were meant to support the secondary market and generate acceptable returns. Freddie Mac’s balance has been more stable this year.
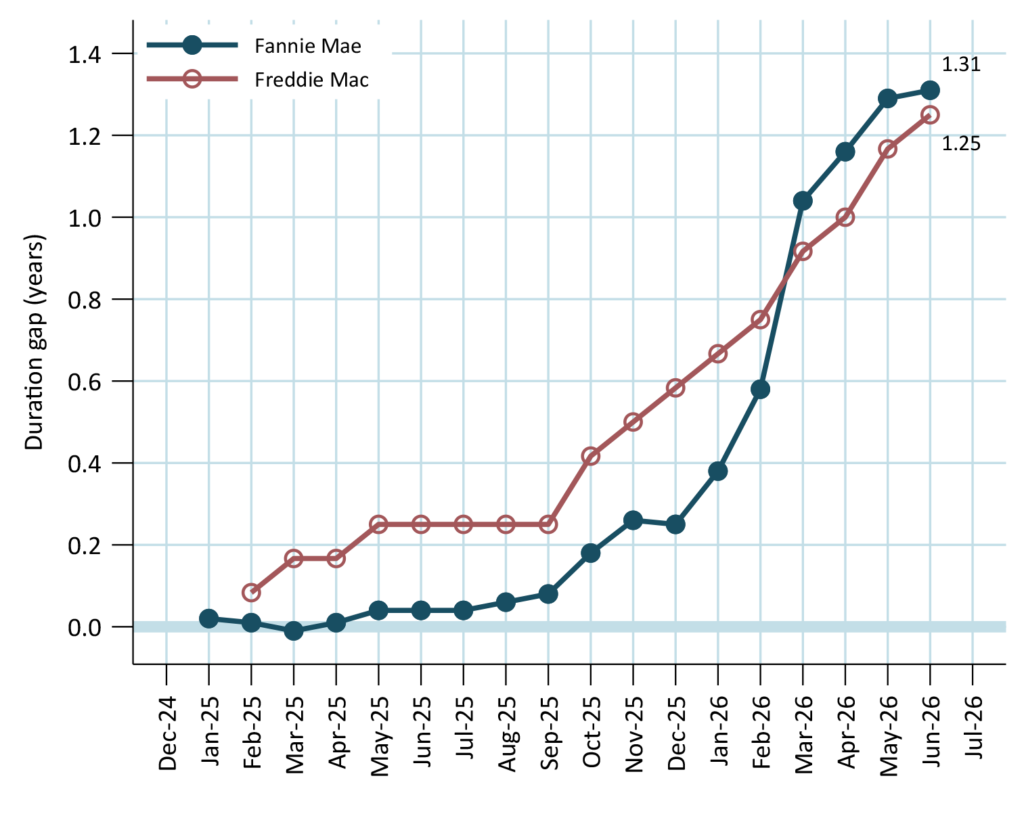
Interest rate exposure continued to rise (Exhibit 2). Fannie Mae’s duration gap ended June at about 1.31 years, up from 1.29 in May. Freddie Mac’s averaged 1.25 years, up from 1.17. A 1.31-year gap means Fannie Mae’s net portfolio value would be expected to fall about 1.31% if rates rose 100 basis points and rise about 1.31% if rates fell by the same amount, before convexity and other nonlinear effects.
Exhibit 2. Interest rate exposure keeps growing
Source: Fannie Mae, Freddie Mac, Santander US Capital Markets.
The increase reflects a choice to retain more long-term rate exposure instead of fully hedging the equity-supported portion of the portfolios. Fannie Mae said its interest rate strategy now balances sensitivity to market values with earnings volatility from short-term rate changes.
Freddie Mac reports duration gaps separately for assets funded mainly by debt and for all other financial instruments. In June, the gap for debt-funded assets rounded to zero months; the other category was 58 months. The total gap of 15 months implies leverage of about 3.9 times, up from about 3.6 times in May.
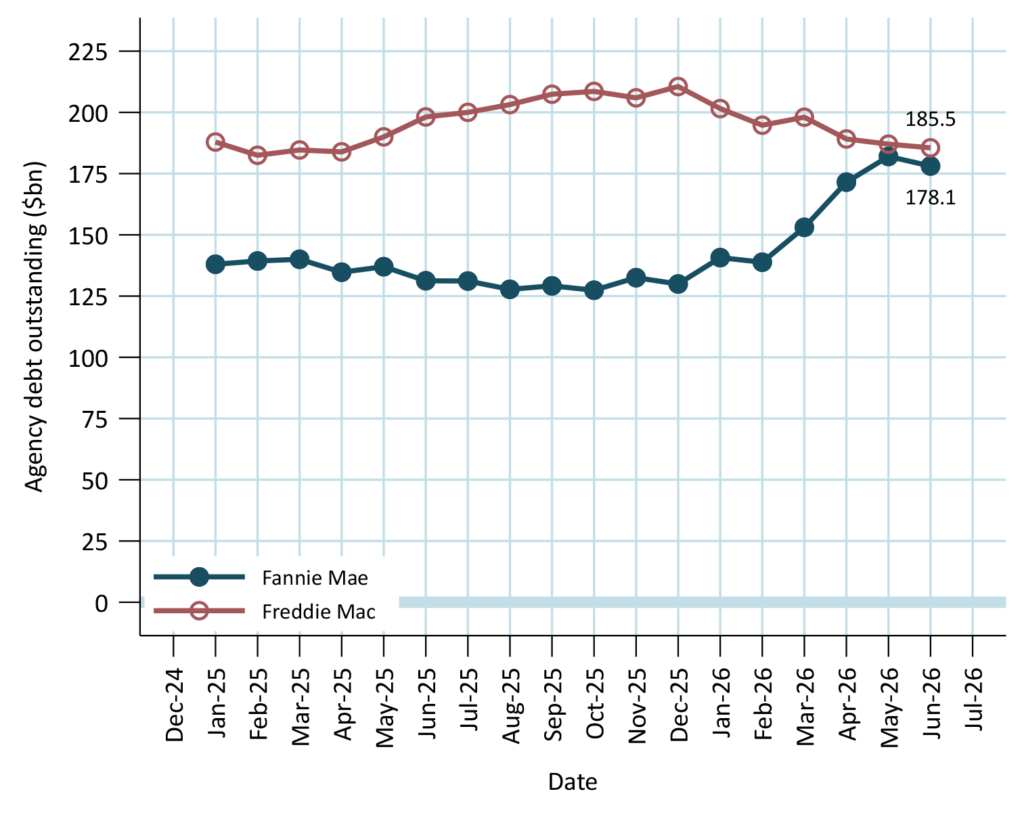
Fannie Mae had been a net debt issuer for most of the year, but that streak ended in June (Exhibit 3). Outstanding debt fell $3.9 billion after growing an average of $10.4 billion a month from January through May.
Exhibit 3. Fannie Mae’s debt balance fell slightly in June
Source: Fannie Mae, Freddie Mac, Santander US Capital Markets.
For MBS investors, June points to modest net demand rather than a fixed purchase schedule. That supports demand, but monthly balances suggest purchases still depend on market conditions and portfolio economics. The clearer trend is rising duration exposure. As their portfolios grow, the GSEs are clearly taking more rate risk.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.