The Long and Short
Non-index APTV bonds offer an attractive discount
This material is a Marketing Communication and does not constitute Independent Investment Research.
Aptiv PLC (APTV: Baa2/BBB/BBB) tendered for more than $1 billion of outstanding notes this year as it spun off its electric distribution systems unit. The move left several debt tranches below the $300 million threshold for index eligibility. Those bonds appropriately trade at a discount to comparable index-eligible debt from APTV and its peers. At current valuations, several look attractive for buy-and-hold investors who do not require index eligibility.
APTV management showed its commitment to mid-BBB leverage in May by using proceeds from the EDS spinoff to fund the tender offer and reduce debt. S&P and Fitch affirmed their ratings and moved their outlooks to stable late last year, citing the planned spinoff and debt reduction. Future acquisitions remain a credit risk, but management has shown that it intends to preserve the ratings. Its recent growth strategy also has favored smaller, strategic bolt-on acquisitions. APTV does not pay a dividend. It repurchased $75 million of shares in the first quarter and had $2 billion left under its $5 billion authorization as of March 31, 2026.
APTV redeemed $1.85 billion of debt with spinoff proceeds and another $266 million with cash. In early April, management launched a cash tender offer for $1.37 billion of senior unsecured debt. The redemptions included $456.5 million of the 3.25% notes due in 2032, $370.5 million of the 5.15% notes due in 2034, $303.8 million of the 5.75% notes due in 2054, $123.5 million of the 5.4% notes due in 2049, $111.7 million of the 4.4% notes due in 2046 and $79.6 million of the 4.15% notes due in 2052. The 3.10% notes due in 2051 were the seventh and lowest-priority tranche in the offer, but no holders participated. Five of the six redeemed tranches fell below the index-eligibility threshold. More capital actions are possible if APTV sheds other businesses, but they appear less likely soon.
Investors appear well compensated for the lower liquidity of APTV’s non-index bonds in the 20-year part of the curve. The bonds also compare favorably with index-eligible APTV debt and auto-parts peers such as LEA and BWA. The APTV notes due in 2046 and 2049 trade about 15 to 20 bp wider on a G-spread basis than index-eligible tranches with slightly longer maturities (Exhibit 1).
Exhibit 1: APTV credit curve versus investment-grade automotive parts peers (marker size indicates deal size)
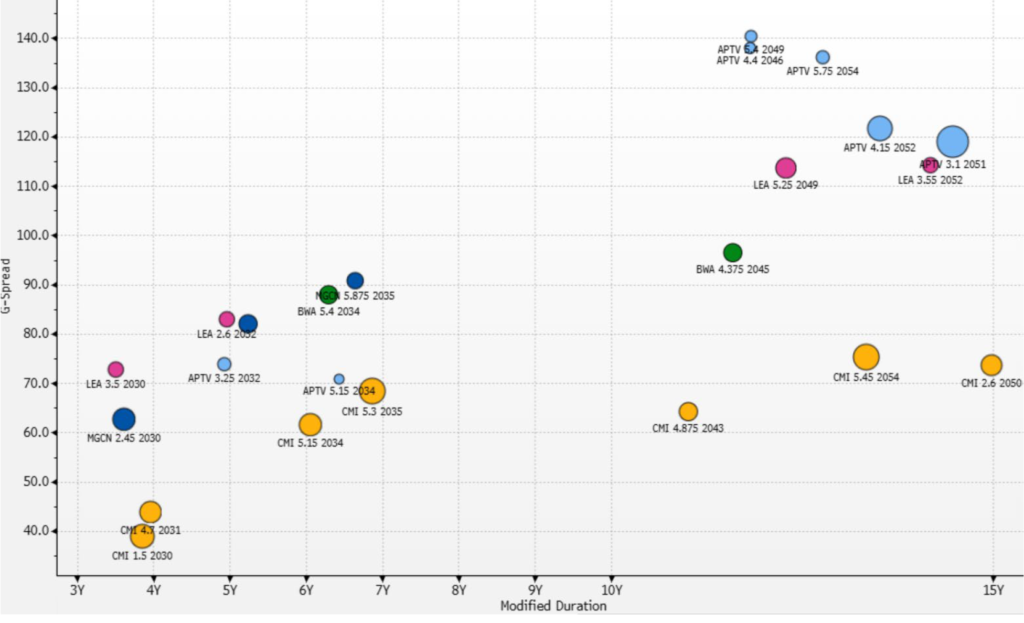
Source: Santander US Capital Markets LLC, Bloomberg/TRACE spread/price indications only
APTV is less a traditional auto-parts maker than a technology supplier to the industry. Its products support autonomous driving and next-generation electric vehicles. The EDS spinoff reduced the company’s scale, with sales falling from about $20 billion last year to a projected $12 billion in 2026. But it also improved diversification. About 25% of revenue is now expected to come from outside passenger vehicles, making the business less cyclical. Other markets include commercial, industrial, data and telecommunications, and aerospace and defense.
The EDS spinoff also should lift APTV’s profit margins. EBITDA margins are expected to reach about 20% within one or two years, up from 15.7% last year. Most peers operate at 7% to 18%. Last year, EDS margins were about 8%, compared with about 17% for the other engineered components group businesses and 11% to 12% for advanced safety and user experience.
APTV’s global revenue mix helps limit tariff exposure if US trade tensions rise again. In 2025, North America accounted for 37% of revenue, Europe, the Middle East and Africa 32%, and Asia-Pacific 29%. In the first quarter of 2026, those shares were about 38%, 32% and 27%, respectively. Most products sold in the U.S. are made in North America, further reducing tariff risk. APTV is incorporated in Jersey and based in Switzerland.
APTV has strong liquidity after the spinoff and limited near-term maturities following debt reductions in 2025 and early redemptions in 2026. It reported $3.17 billion of cash at the end of the first quarter of 2026. After the tender offers, cash and equivalents likely will be about $1 billion to $1.3 billion on a pro forma basis in the next earnings report. APTV also has a $2.85 billion revolving credit facility through 2030. Its only relatively near-term public debt maturity is $569 million due in 2028. The next is $800 million due in 2031, with most debt maturing later.
Recent second-quarter earnings reports point to favorable conditions in the auto sector. Ford Motor Co., in particular, reported strong results this week. APTV does not disclose revenue by automaker, but Ford is among its largest customers and accounted for an estimated 11% of sales in the second half of last year. In recent years, APTV’s five largest auto customers have generated about 40% of sales, and the top 10 about 55% to 56%.
This material is intended only for institutional investors and does not carry all of the independence and disclosure standards of retail debt research reports. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This message, including any attachments or links contained herein, is subject to important disclaimers, conditions, and disclosures regarding Electronic Communications, which you can find at https://portfolio-strategy.apsec.com/sancap-disclaimers-and-disclosures.
Important Disclaimers
Copyright © 2026 Santander US Capital Markets LLC and its affiliates (“SCM”). All rights reserved. SCM is a member of FINRA and SIPC. This material is intended for limited distribution to institutions only and is not publicly available. Any unauthorized use or disclosure is prohibited.
In making this material available, SCM (i) is not providing any advice to the recipient, including, without limitation, any advice as to investment, legal, accounting, tax and financial matters, (ii) is not acting as an advisor or fiduciary in respect of the recipient, (iii) is not making any predictions or projections and (iv) intends that any recipient to which SCM has provided this material is an “institutional investor” (as defined under applicable law and regulation, including FINRA Rule 4512 and that this material will not be disseminated, in whole or part, to any third party by the recipient.
The author of this material is an economist, desk strategist or trader. In the preparation of this material, the author may have consulted or otherwise discussed the matters referenced herein with one or more of SCM’s trading desks, any of which may have accumulated or otherwise taken a position, long or short, in any of the financial instruments discussed in or related to this material. Further, SCM or any of its affiliates may act as a market maker or principal dealer and may have proprietary interests that differ or conflict with the recipient hereof, in connection with any financial instrument discussed in or related to this material.
This material (i) has been prepared for information purposes only and does not constitute a solicitation or an offer to buy or sell any securities, related investments or other financial instruments, (ii) is neither research, a “research report” as commonly understood under the securities laws and regulations promulgated thereunder nor the product of a research department, (iii) or parts thereof may have been obtained from various sources, the reliability of which has not been verified and cannot be guaranteed by SCM, (iv) should not be reproduced or disclosed to any other person, without SCM’s prior consent and (v) is not intended for distribution in any jurisdiction in which its distribution would be prohibited.
In connection with this material, SCM (i) makes no representation or warranties as to the appropriateness or reliance for use in any transaction or as to the permissibility or legality of any financial instrument in any jurisdiction, (ii) believes the information in this material to be reliable, has not independently verified such information and makes no representation, express or implied, with regard to the accuracy or completeness of such information, (iii) accepts no responsibility or liability as to any reliance placed, or investment decision made, on the basis of such information by the recipient and (iv) does not undertake, and disclaims any duty to undertake, to update or to revise the information contained in this material.
Unless otherwise stated, the views, opinions, forecasts, valuations, or estimates contained in this material are those solely of the author, as of the date of publication of this material, and are subject to change without notice. The recipient of this material should make an independent evaluation of this information and make such other investigations as the recipient considers necessary (including obtaining independent financial advice), before transacting in any financial market or instrument discussed in or related to this material.
Important disclaimers for clients in the EU and UK
This publication has been prepared by Trading Desk Strategists within the Sales and Trading functions of Santander US Capital Markets LLC (“SanCap”), the US registered broker-dealer of Santander Corporate & Investment Banking. This communication is distributed in the EEA by Banco Santander S.A., a credit institution registered in Spain and authorised and regulated by the Bank of Spain and the CNMV. Any EEA recipient of this communication that would like to affect any transaction in any security or issuer discussed herein should do so with Banco Santander S.A. or any of its affiliates (together “Santander”). This communication has been distributed in the UK by Banco Santander, S.A.’s London branch, authorised by the Bank of Spain and subject to regulatory oversight on certain matters by the Financial Conduct Authority (FCA) and the Prudential Regulation Authority (PRA).
The publication is intended for exclusive use for Professional Clients and Eligible Counterparties as defined by MiFID II and is not intended for use by retail customers or for any persons or entities in any jurisdictions or country where such distribution or use would be contrary to local law or regulation.
This material is not a product of Santander´s Research Team and does not constitute independent investment research. This is a marketing communication and may contain ¨investment recommendations¨ as defined by the Market Abuse Regulation 596/2014 ("MAR"). This publication has not been prepared in accordance with legal requirements designed to promote the independence of research and is not subject to any prohibition on dealing ahead of the dissemination of investment research. The author, date and time of the production of this publication are as indicated herein.
This publication does not constitute investment advice and may not be relied upon to form an investment decision, nor should it be construed as any offer to sell or issue or invitation to purchase, acquire or subscribe for any instruments referred herein. The publication has been prepared in good faith and based on information Santander considers reliable as of the date of publication, but Santander does not guarantee or represent, express or implied, that such information is accurate or complete. All estimates, forecasts and opinions are current as at the date of this publication and are subject to change without notice. Unless otherwise indicated, Santander does not intend to update this publication. The views and commentary in this publication may not be objective or independent of the interests of the Trading and Sales functions of Santander, who may be active participants in the markets, investments or strategies referred to herein and/or may receive compensation from investment banking and non-investment banking services from entities mentioned herein. Santander may trade as principal, make a market or hold positions in instruments (or related derivatives) and/or hold financial interest in entities discussed herein. Santander may provide market commentary or trading strategies to other clients or engage in transactions which may differ from views expressed herein. Santander may have acted upon the contents of this publication prior to you having received it.
This publication is intended for the exclusive use of the recipient and must not be reproduced, redistributed or transmitted, in whole or in part, without Santander’s consent. The recipient agrees to keep confidential at all times information contained herein.